Staged Financing Beyond the Venture Record: Equity Rounds in the Accounts of Italian SMEs (Research Square)
Summary
- The dataset covers 3,225 certified innovative SMEs over 2016–2025, observing 2,991 priced capital increases across 1,330 firms.p.2
- Capital increases above 1 per cent of total assets had a median size of 350 thousand euro and a ninety-fifth percentile of 5.4 million.p.10
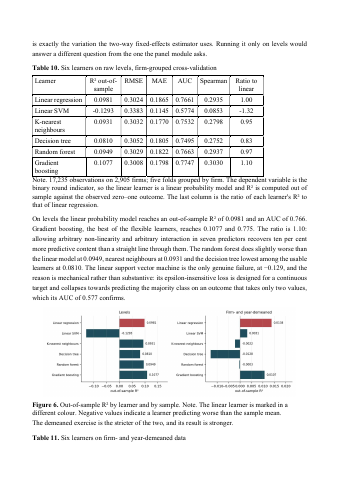
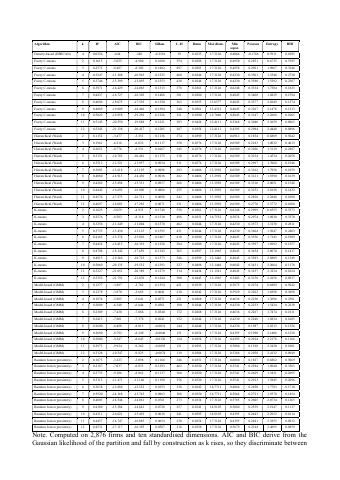
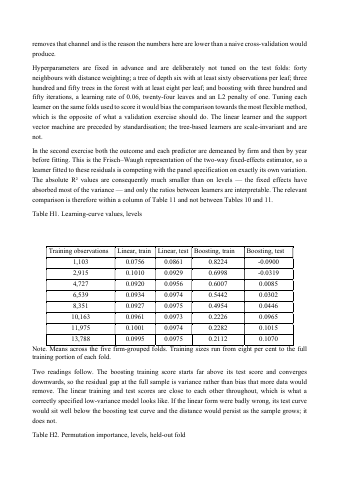
- Gradient boosting attained an out-of-sample R² of 0.1077 on raw levels compared to 0.0981 for linear regression.p.21
- Across 2,991 material equity rounds, total capital raised amounted to €4,218.8 million.p.32
Key insights
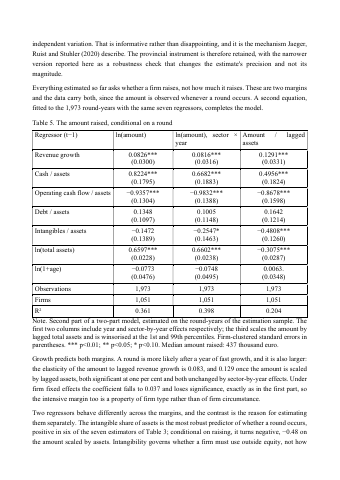
- Selection into outside equity rounds operates on firm revenue growth rather than accounting profitability.p.2
- Deepening operating losses and intangible asset additions occur after an equity round rather than before it.p.3
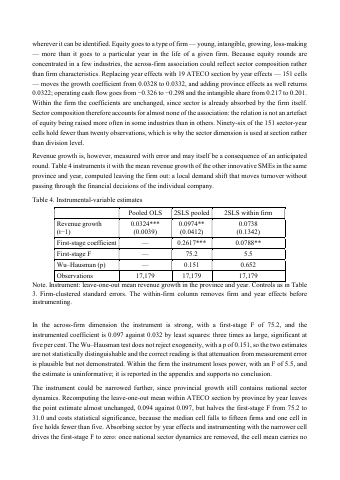
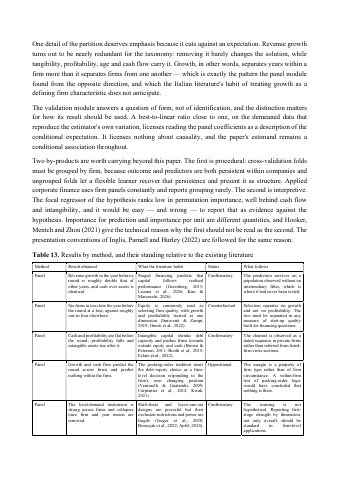
- The relationship between firm growth and equity rounds exists across firms but disappears in within-firm estimators.p.12
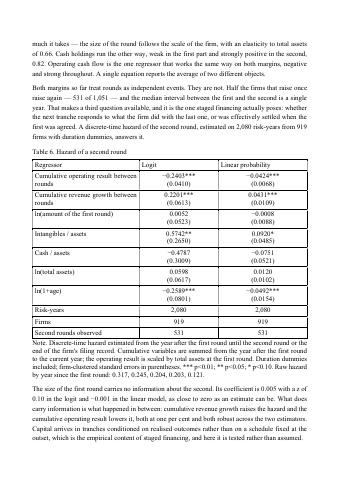
- The size of an initial funding round carries no statistical information regarding the probability of a subsequent round.p.15
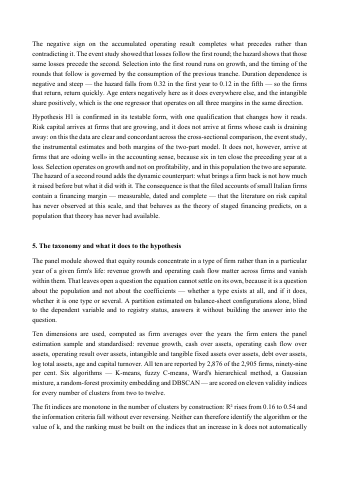
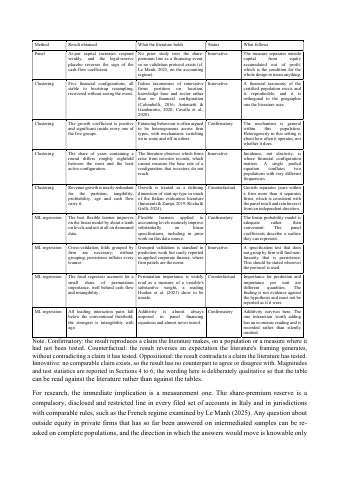
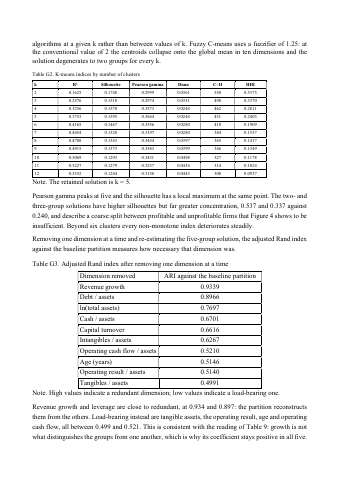
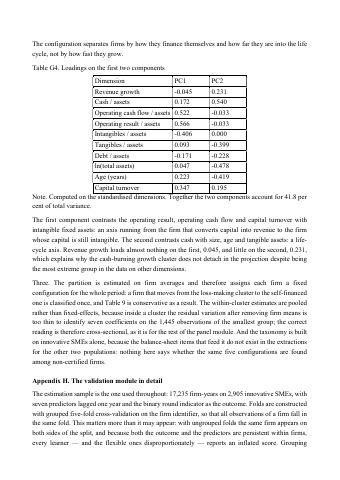
- Unsupervised financial taxonomy identifies five stable enterprise configurations that do not mirror industry classifications.p.19
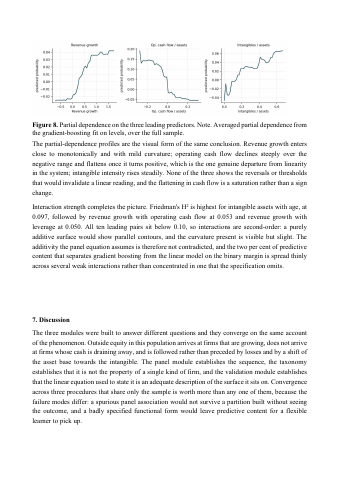
- Growth remains a positive predictor of capital rounds across all five financial configurations, though event frequency differs up to eightfold.p.20
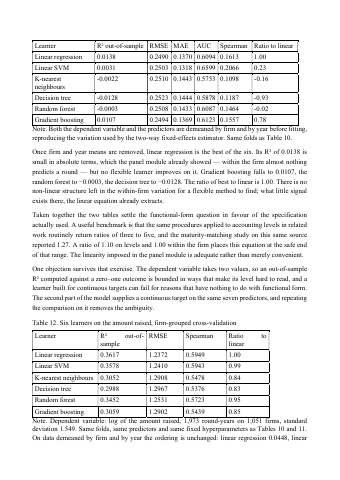
- Non-linear machine learning models fail to improve upon linear probability models when evaluated on firm- and year-demeaned data.p.22
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
 p.8
 p.9
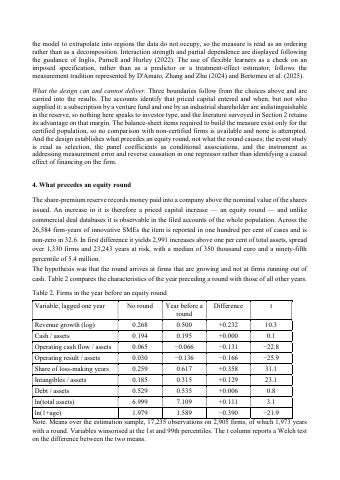 p.10
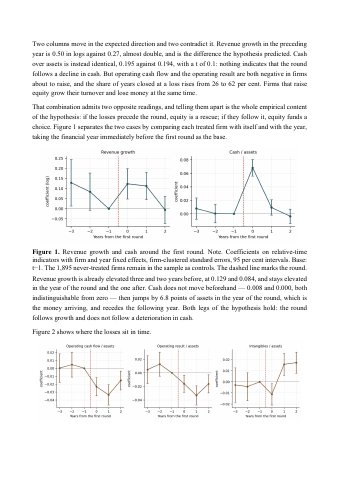 p.11
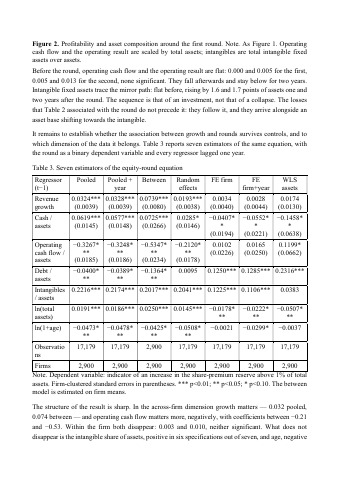 p.12
 p.13
 p.14
 p.15
 p.16
 p.17
 p.18
 p.19
 p.20
 p.21
 p.22
 p.23
 p.24
 p.25
 p.26
 p.27
 p.28
 p.29
 p.30
 p.31
 p.32
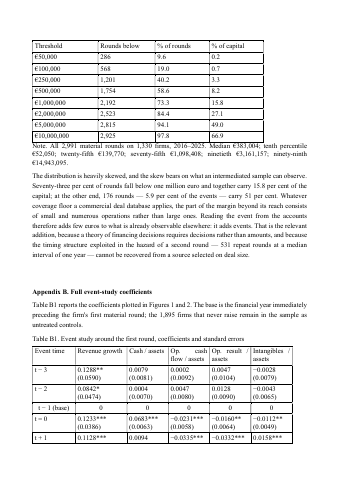 p.33
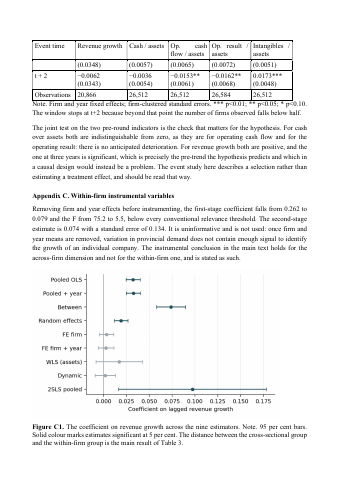 p.34
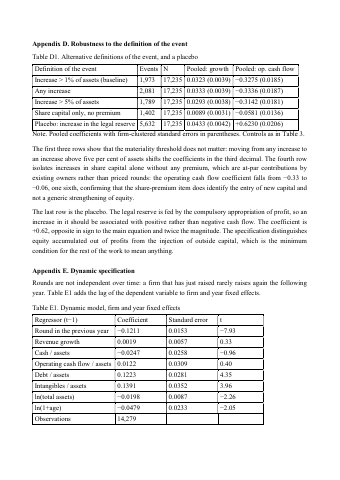 p.35
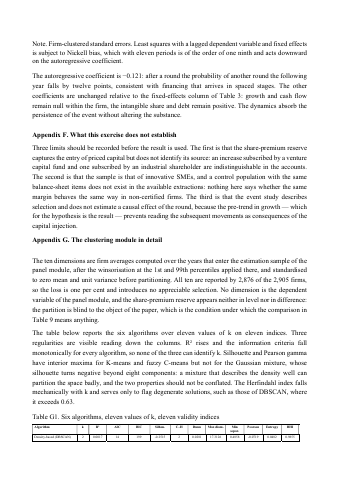 p.36
 p.37
 p.38
 p.39
 p.40
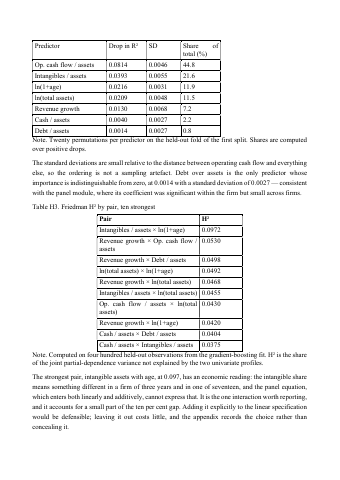 p.41
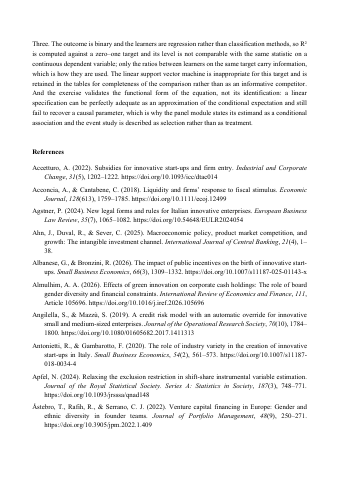 p.42
 p.43
 p.44
 p.45
 p.46
 p.47
 p.48
 p.49
 p.50
 p.51
 p.52
 p.53
 p.54
 p.55
 p.56
 p.57
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.