The ECB May Already Be Captured by Fiscal Dominance (Archives of Business Research)
SaveSummary
- The European Commission forecasts France's fiscal deficit at around 5% of GDP in 2026.p.4
- France's public debt ratio is expected to reach approximately 118% of GDP in 2026 and around 120% by 2027.p.4
- Growth in France is projected to remain modest, at around 1% per year.p.4
- The ECB's Transmission Protection Instrument (TPI) was announced in July 2022.p.5
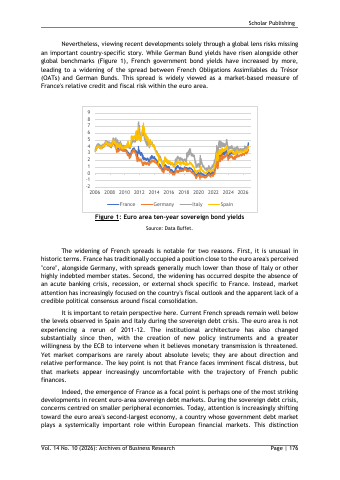
- French spreads over German Bunds have widened, but remain well below Spain and Italy during the 2011-12 sovereign debt crisis.p.3
- Market-implied ratings show a negative gap for France, meaning markets are more optimistic than rating agencies.p.8
- The paper argues expectations of possible ECB intervention risk blurring monetary and fiscal policy, though France does not currently require support.p.14
Key insights
- French government bond yields have risen by more than German Bund yields, widening the OAT-Bund spread.p.3
- The widening of French spreads occurred without an acute banking crisis, recession or France-specific external shock.p.3
- The TPI criterion that moves be not warranted by country-specific fundamentals is difficult to apply objectively.p.6
- Determining whether French spread widening is warranted is an exercise in judgement rather than measurement.p.7
- On the author's ratings gap measure, French yield moves look less disconnected from fundamentals than proponents of intervention suggest.p.8
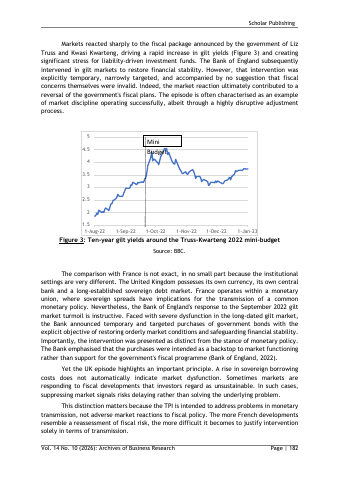
- The Bank of England's September 2022 gilt intervention was temporary and narrowly targeted, unlike an open-ended backstop.p.9
- France's size as the euro area's second-largest economy creates an implicit asymmetry in market discipline compared with smaller states.p.12
- Fiscal dominance can emerge through expectations, without a single bond being purchased under the TPI.p.13
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
 p.8
 p.9
 p.10
 p.11
 p.12
 p.13
 p.14
 p.15
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.