Measuring and comparing investment risks for a sample of cryptocurrencies using the Value at Risk (VAR) model and the Conditional Value at Risk (CVAR) model (Growth Leadership Journal)
Summary
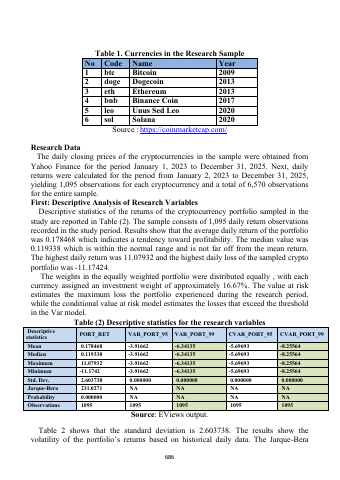
- The dataset includes 1,095 daily observations per cryptocurrency, generating a total of 6,570 observations for analysis in EViews.p.11
- The daily return of the sampled cryptocurrency portfolio averaged 0.178468 with a standard deviation of 2.603738.p.11
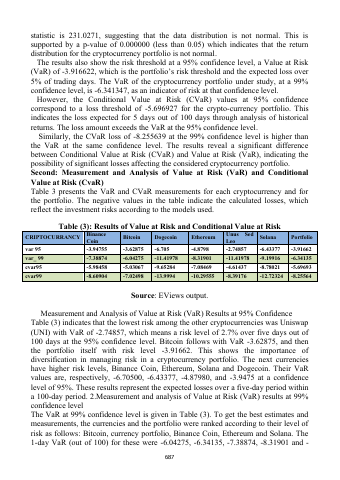
- At a 95% confidence level, the portfolio Value at Risk (VaR) was -3.91662, while the Conditional Value at Risk (CVaR) stood at -5.69693.p.12
- At a 99% confidence level, the portfolio VaR increased to -6.34135 and the CVaR reached -8.25564.p.12
- Bitcoin was identified as the least risky cryptocurrency in the sample with a 99% CVaR of -7.02498, functioning as a safe haven asset.p.13
- Researchers advise limiting cryptocurrency allocations to no more than 5% of a total diversified investment portfolio.p.15
Key insights
- Bitcoin demonstrated the lowest risk profile among the analyzed assets, achieving a 99% CVaR of -7.02498.p.13
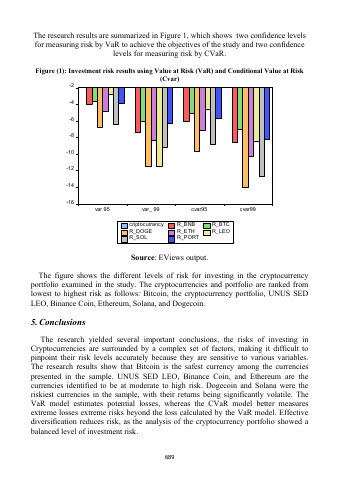
- Solana and Dogecoin recorded the highest investment risk levels, with 99% CVaR losses of -13.9994 and -12.72324 respectively.p.13
- The equally weighted portfolio assigned an investment allocation of approximately 16.67% to each of the 6 sampled cryptocurrencies.p.11
- Portfolio diversification effectively reduced overall risk, resulting in a 99% CVaR of -8.25564, which is lower than the risk levels of individual high-volatility assets.p.13
- A Jarque-Bera statistic of 231.0271 confirmed that cryptocurrency daily returns do not follow a normal distribution.p.12
- Conditional Value at Risk (CVaR) provides a superior estimation of extreme tail losses compared to the traditional Value at Risk (VaR) model.p.14
- The crypto portfolio experienced a maximum daily return of 11.07932 and a maximum daily loss of -11.1742 over the observed period.p.11
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
 p.8
 p.9
 p.10
 p.11
 p.12
 p.13
 p.14
 p.15
 p.16
 p.17
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.