FinTech Financing Platforms and Bank Lending to SMEs in Malaysia: Complements or Substitutes (Information Management and Business Review)
Summary
- In 2024, MSMEs constituted a vital component of Malaysia's economy, accounting for 39.5% of GDP and 48.7% of total employment.p.1
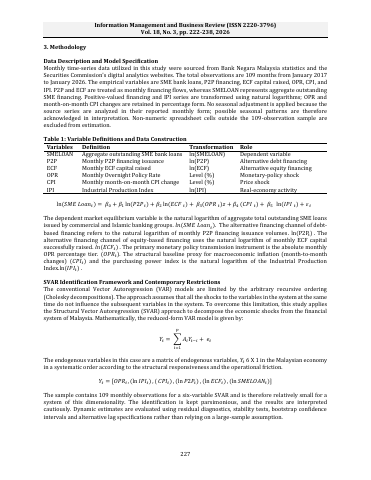
- The study employs a six-variable SVAR framework using 109 monthly observations spanning from January 2017 to January 2026.p.6
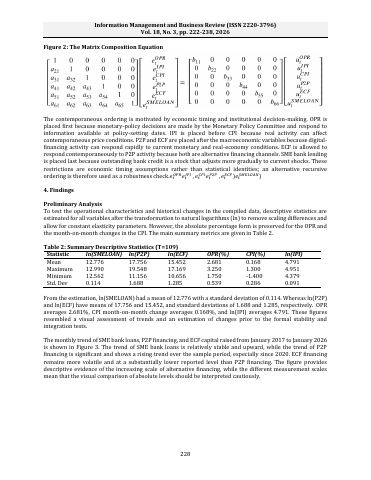
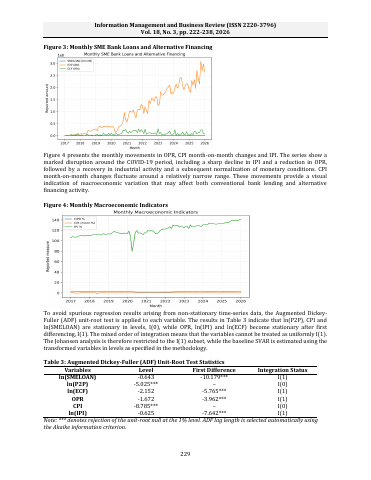
- Descriptive statistics show log-transformed SME bank loans averaged 12.776, while log P2P financing and log ECF capital averaged 17.756 and 15.452, respectively.p.7
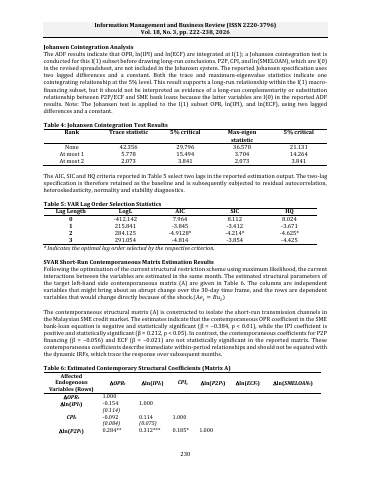
- Contemporaneous structural matrix estimates show the OPR coefficient on SME bank loans is -0.384 (p < 0.01) and the IPI coefficient is 0.212 (p < 0.05).p.9
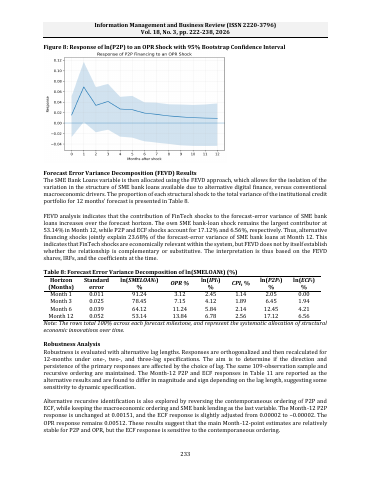
- At a 12-month forecast horizon, own SME bank loan shocks explain 53.14% of forecast error variance, whereas P2P and ECF shocks account for 17.12% and 6.56%, respectively.p.12
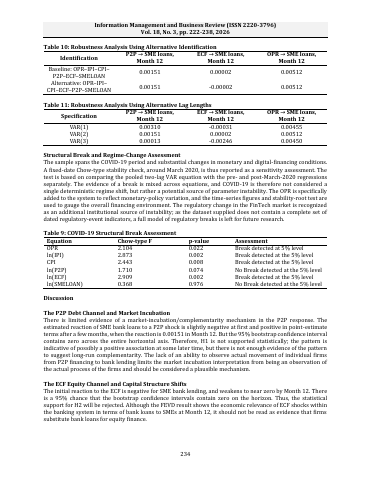
- FinTech financing shocks jointly account for 23.68% of the forecast-error variance of SME bank loans at Month 12.p.12
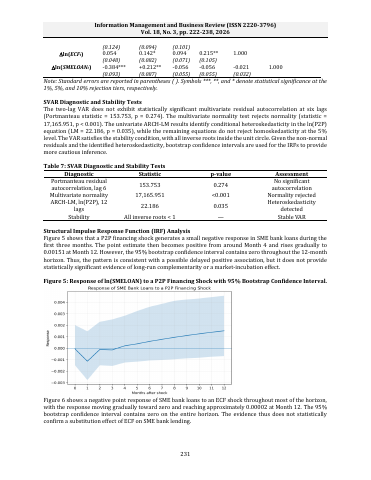
- A P2P financing shock generates a positive point response in SME bank loans reaching 0.00151 at Month 12, though its 95% bootstrap confidence interval includes zero throughout.p.10
Key insights
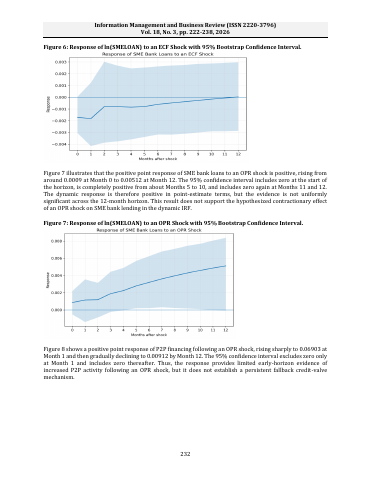
- P2P and ECF shocks generate small dynamic responses in SME bank lending, with 95% bootstrap confidence intervals generally including zero.p.1
- Malaysia established a formal regulatory regime for Equity Crowdfunding in 2015 and for Peer-to-Peer financing in 2016.p.1
- Johansen cointegration tests indicate one cointegrating relationship at the 5% level within the I(1) macro-financing subset of OPR, log IPI, and log ECF.p.9
- Contemporaneous coefficients for P2P financing (-0.056) and ECF (-0.021) are not statistically significant in the short-run structural matrix.p.9
- FinTech shocks jointly account for 23.68% of the forecast-error variance of SME bank loans by Month 12, demonstrating economic relevance.p.12
- An OPR shock produces a positive point response in SME bank lending that reaches 0.00512 at Month 12 and is statistically significant between Months 5 and 10.p.11
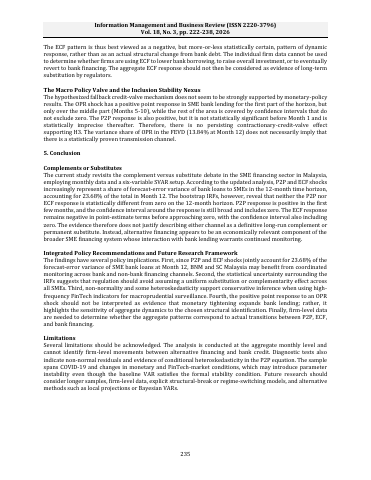
- Following an OPR shock, P2P financing rises sharply to 0.06903 at Month 1, but the response is statistically distinguishable from zero only at that initial horizon.p.11
- Aggregate empirical evidence does not provide robust support for a definitive complementarity, substitution, or credit-valve mechanism between FinTech platforms and SME bank lending.p.1
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
 p.8
 p.9
 p.10
 p.11
 p.12
 p.13
 p.14
 p.15
 p.16
 p.17
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.