Common Policy Communication and Sovereign Yield Curves (Research Square)
Summary
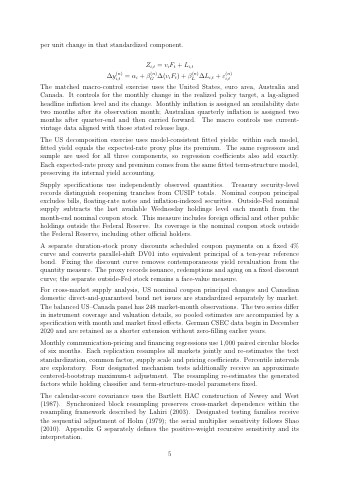
- Between 2014-2019 and 2020-2025, two-year yield commonality rose from 45.2% to 56.4%, while ten-minus-two-year slope commonality declined from 66.7% to 56.4%.p.2
- The communication analysis corpus covers 559 official central bank communications across six major sovereign bond markets.p.2
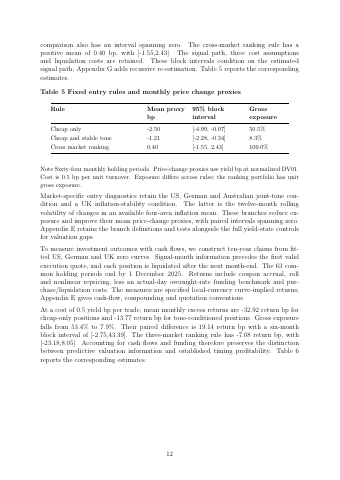
- Applying a joint common and local tone condition reduces average exposure from 50.5% to 8.3% in the six-market price-change exercise.p.2
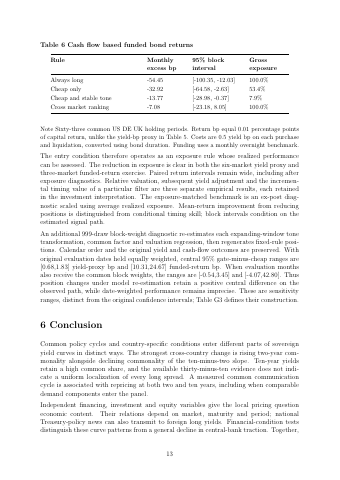
- In a cash-flow return test over 63 holding periods, funded mean excess returns rise from -32.92 to -13.77 basis points when applying the tone condition.p.13
Key insights
- Across six sovereign bond markets, two-year yield commonality increased by 11.27 percentage points after 2019 while ten-minus-two-year slope commonality fell by 10.31 points.p.2
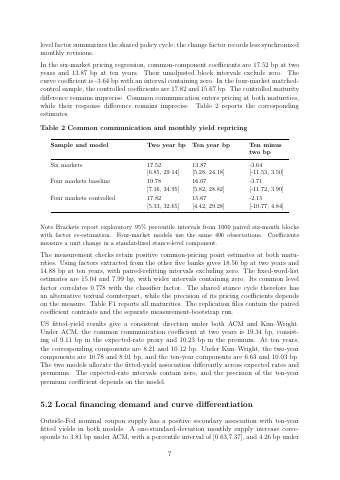
- A one-standard-deviation monthly increase in outside-Fed nominal Treasury supply corresponds to a 3.81 bp increase in ten-year fitted yields under ACM.p.8
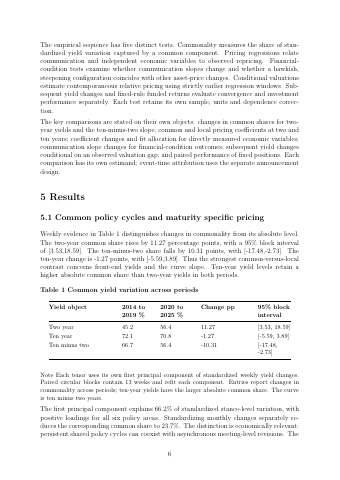
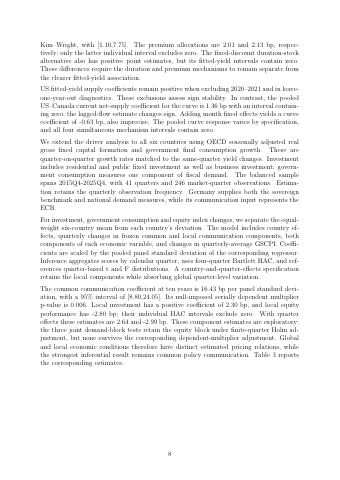
- Panel regressions across six countries show that a one-standard-deviation change in common policy communication is associated with a 16.43 bp shift in ten-year yields.p.9
- One source-sample standard deviation of US Treasury-policy news generates 1.47 bp of Canadian and 1.87 bp of UK ten-year yield repricing.p.10
- Incorporating a stable tone condition into bond entry rules reduces funded cash-flow excess return losses from -32.92 bp to -13.77 bp while decreasing exposure from 53.4% to 7.9%.p.13
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
 p.8
 p.9
 p.10
 p.11
 p.12
 p.13
 p.14
 p.15
 p.16
 p.17
 p.18
 p.19
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.