The Impact of Sustainability and Climate Disclosure in Enhancing Future Cash Flows of the Economic Unit: An Applied Study on Industrial Companies (Acta Innovations)
SaveSummary
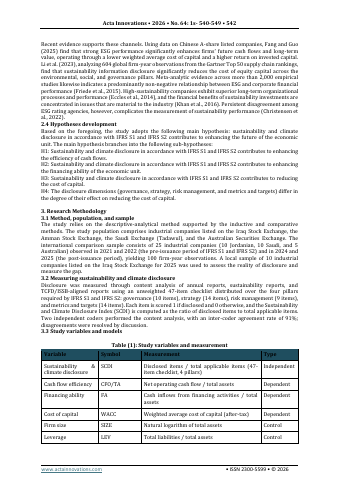
- The international comparison sample includes 25 industrial companies across Jordan, Saudi Arabia, and Australia, providing 100 firm-year observations across pre-issuance (2021–2022) and post-issuance (2024–2025) periods of IFRS S1 and IFRS S2.p.1
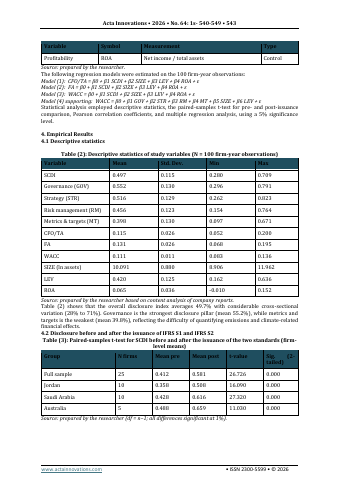
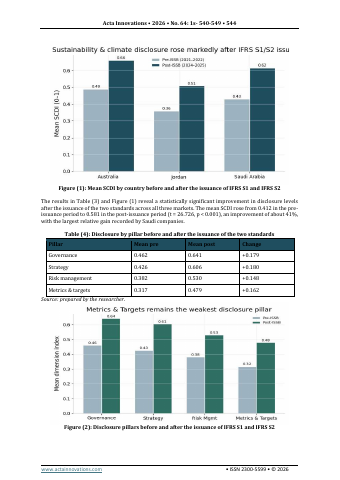
- Following the issuance of IFRS S1 and IFRS S2, the mean Sustainability and Climate Disclosure Index (SCDI) across the international sample increased from 0.412 to 0.581, reflecting an improvement of about 41%.p.5
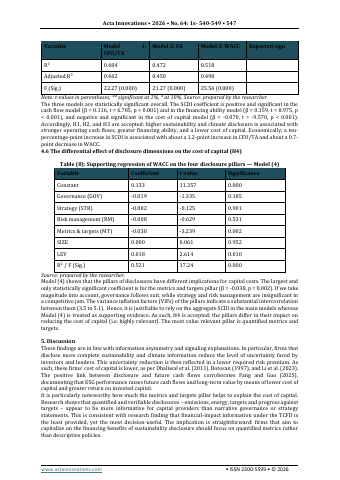
- Multiple regression analysis indicates that SCDI is positively associated with cash flow efficiency (beta = 0.116, t = 6.785) and financing ability (beta = 0.159, t = 8.975).p.8
- Regression results confirm that higher disclosure levels under IFRS S1 and IFRS S2 are negatively associated with the weighted average cost of capital (beta = -0.070, t = -9.570).p.8
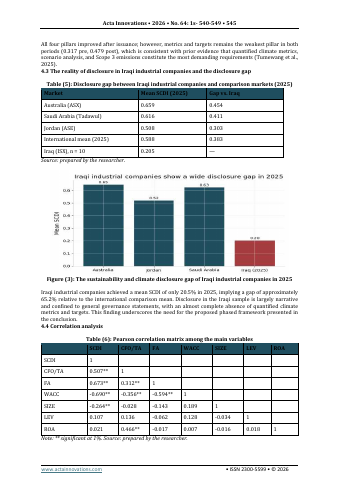
- Among the four disclosure pillars, metrics and targets has the largest and only statistically significant effect on reducing WACC (beta = -0.038, p = 0.002).p.8
- To address the local gap, the study proposes a three-phase roadmap for applying IFRS S1 and IFRS S2 in Iraq: preparation and awareness, early voluntary adoption, and gradual mandatory application.p.9
Key insights
- Implementation of IFRS S1 and IFRS S2 significantly increased overall disclosure levels across international industrial markets from a mean of 0.412 to 0.581.p.5
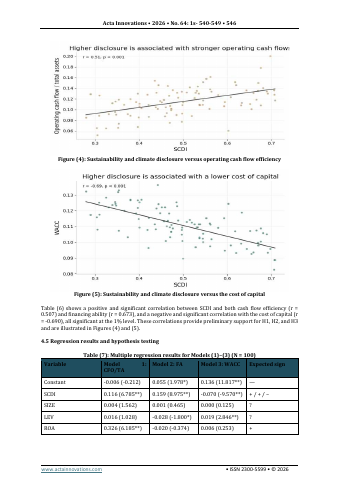
- Pearson correlation reveals a strong positive association between disclosure level and financing ability (r = 0.673) and a strong negative association with cost of capital (r = -0.690).p.6
- Economically, a 10-percentage-point increase in the disclosure index is associated with approximately a 1.2-point increase in operating cash flow to total assets and a 0.7-point reduction in WACC.p.8
- The metrics and targets pillar serves as the primary driver in reducing cost of capital due to its reliance on quantified climate metrics and financial effects.p.8
- High intercorrelation exists among the individual disclosure pillars, with variance inflation factors ranging between 3.5 and 5.1.p.8
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
 p.8
 p.9
 p.10
Funders mentioned
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.