Responsible Digital Credit Scoring as a Factor of Banking System Stability and Financial Inclusion in Uzbekistan (YASHIL IQTISODIYOT VA TARAQQIYOT)
Summary
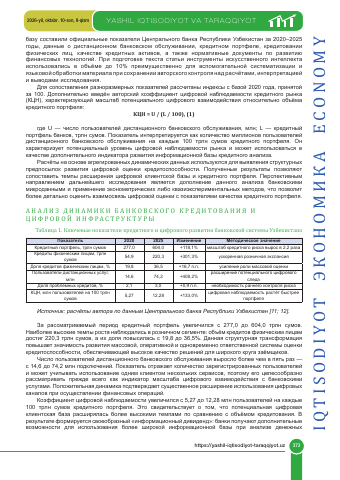
- The total bank credit portfolio in Uzbekistan expanded from 277.0 to 604.0 trillion UZS between 2020 and 2025, representing a growth of +118.1%.p.11
- The share of individual loans within the aggregate bank credit portfolio rose from 19.8% in 2020 to 36.5% in 2025.p.11
- The number of remote banking service users grew by +408.2% from 14.6 million in 2020 to 74.2 million in 2025.p.11
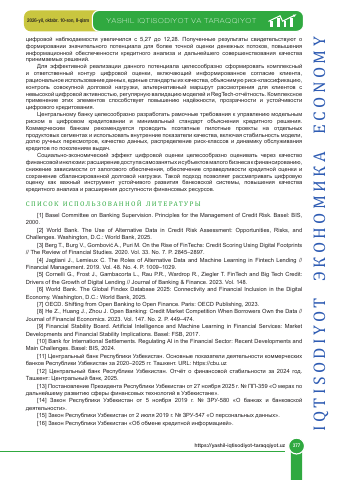
- The digital observability coefficient of the credit market increased by +133.0% from 5.27 to 12.28 million users per UZS 100 trillion portfolio.p.11
Key insights
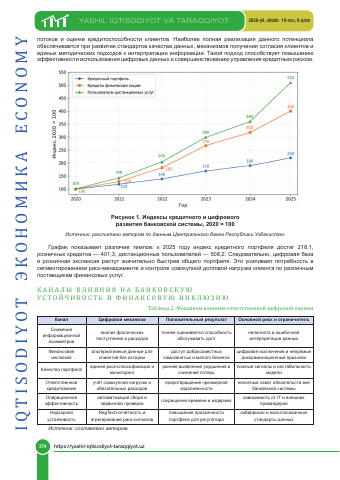
- The digital observability base expanded at a faster pace than the bank credit portfolio volume, creating information capacity for improved creditworthiness scoring.p.9
- Transaction analysis and income regularity tracking help reduce information asymmetry by assessing actual cash flows and debt service capability.p.10
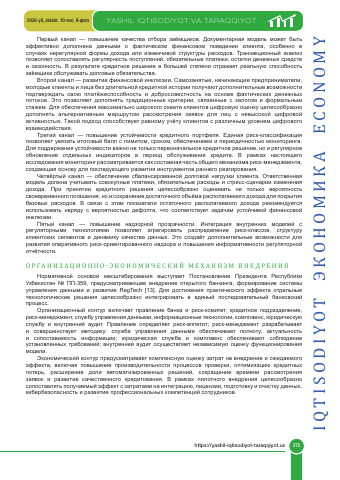
- Alternative digital data enables self-employed individuals and small enterprises lacking traditional credit histories to access formal financing.p.13
- Establishing alternative application review paths protects low digital activity clients from algorithmic exclusion and discrimination.p.13
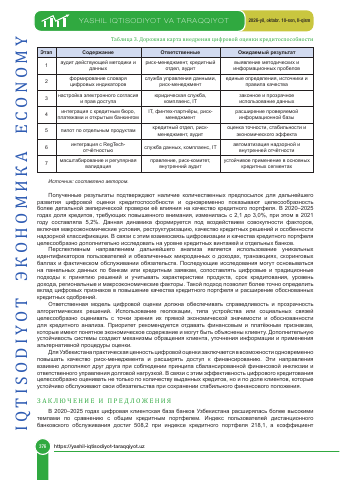
- Integrating internal risk classification models with RegTech technologies improves reporting transparency and enables early risk detection.p.13
- Presidential Decree No. PP-359 serves as the main regulatory foundation for implementing open banking, data management, and RegTech in Uzbekistan.p.13
- Loans requiring heightened attention peaked at 5.2% in 2021 before settling at 3.0% in 2025.p.14
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
 p.8
 p.9
 p.10
 p.11
 p.12
 p.13
 p.14
 p.15
 p.16
 p.17
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.