State of European Tech 2024
Europe's tech workforce reached 3.5M employees in 2024, expanding at a 24% compounded annual growth rate since 2015.
174 documents
Europe's tech workforce reached 3.5M employees in 2024, expanding at a 24% compounded annual growth rate since 2015.
The cumulative enterprise value of European startups and scaleups has grown by approximately EUR 2,5 tn since 2012.
European venture capital firms receive an average of 851 investment proposals per year, with 6% leading to closed deals.
In 2021, there were more than 300 million users of digital payments and more than 30 million users of digital banks across Latin America.
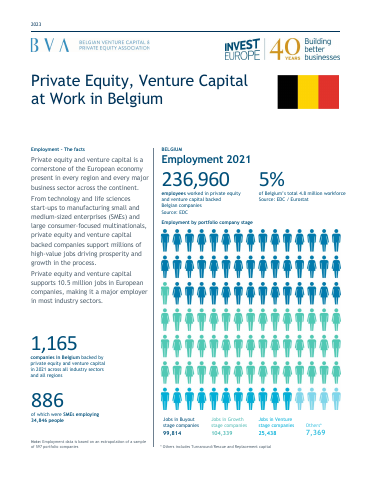
Private equity and venture capital backed companies employed 236,960 people in Belgium in 2021, representing 5% of the country's total 4.8 million workforce.
ICT/Fintech surpassed CHF 2 billion, with ICT invested capital growing by 72%.
Private capital entities managed €43.629 million across 3.012 Spanish portfolio companies in 2021.
Private capital in Spain invested an all-time record total volume of €9,238 million across 960 operations in 2022.
European tech ecosystem value bounced back to $3 trillion, recovering the $400 billion that was wiped out in 2022.
Combining 2021 and 2022 accounted for one third of all VC volumes invested since 2007.
Tech Titans increased their market cap by 36% over the past year, adding $2.4T in value.
In the first half of 2022, total invested capital in Swiss start-up financing rose to almost CHF 2.6 billion across more than 160 financing rounds.
In 2021, Private Equity and Venture Capital in Spain invested a total volume of €7.572,7M across a record 933 investments.
SICTIC facilitated 110 funding rounds in 2021, accounting for 71% of all early-stage ICT investments in Switzerland.
ICT/Fintech investment more than doubled to achieve a record volume of over CHF 1.5 billion.
Canadian health tech venture funding totaled $672M across 168 deals in 2022, down 30% from the previous year with an average deal size of $4M.
Investments in Swiss start-ups recorded an increase of 44 % in invested capital, reaching 3059 CHF m in 2021.
Software and cloud giants with valuations above $100B lost approximately ~35% of their market capitalization.
Participating federal agencies obligated $4.12 billion in SBIR funding and $618.3 million in STTR funding, totaling $4.73 billion in FY22.
In Vienna, 44 financing rounds were completed in 2021 (as of July 22), with investment volume increasing from €121 million in the previous year to €464 million.
European VC delivered EUR 12bn in new investment volumes in 2020, representing 7% growth over the previous year.
Investment in Swiss start-ups reached CHF 1.7 billion across 124 financing rounds in the first half of 2021.
Microsoft represents c. 55% of total market value among software and cloud companies above $100bn in market cap.
Swiss venture capital investment experienced a 7% decrease overall.
Private equity backed portfolio companies created 173,124 net jobs in 2018, achieving an employment growth rate of 5.5%.
During the first half of 2020, CHF 763 million was invested into Swiss start-ups across 105 financing rounds.
European VC-backed companies raised $7.9B across 804 deals in Q4'19.
Venture capital investment in private cloud companies in Europe and Israel reached $9-9.5bn YTD 2020, up from $7-7.5bn in 2019 YTD.
According to Copenhagen Economics analysis, Swedish GDP is currently 0.8% higher than it would otherwise be due to venture capital.
The 2018/2019 academic year was a record year for spinout exits from UK universities, with sales of spinout company shares totalling more than £61 million, an increase of 37% from 2017/2018.