Validating a Growth Equity Investment Thesis for an Advanced Semiconductor Packaging Company (Finance & Economics)
Summary
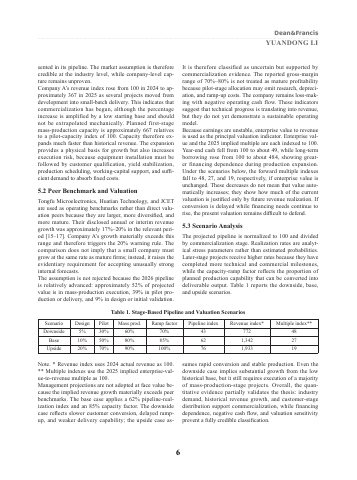
- Company A's revenue index rose from 100 in 2024 to approximately 367 in 2025 as projects moved to small-batch delivery.p.6
- Planned first-stage mass-production capacity is set at approximately 667 relative to a pilot-capacity index of 100.p.6
- Mature listed semiconductor-packaging peers recorded annual or interim revenue growth of approximately 17%–20%.p.6
- The 2026 projected pipeline comprises 52% in mass-production execution, 39% in pilot production or delivery, and 9% in design or initial validation.p.6
- The top quartile of customers accounts for about 65% of projected order value, introducing significant customer concentration.p.7
- More than half of the aggregate value across five core equipment categories is sourced overseas.p.7
Key insights
- Growth equity investors reframe due diligence as an assumption-based decision process linking technological promise to observable commercial milestones.p.2
- Target growth forecasts that exceed peer medians by more than 20% are flagged as uncertain and require strong external validation.p.4
- Company A's revenue index increased from 100 in 2024 to approximately 367 in 2025 following pilot production milestones.p.6
- First-stage mass-production capacity expands to 667 from a pilot baseline of 100, heightening fixed-cost absorption risk.p.6
- Major customers in the top quartile represent approximately 65% of total projected order pipeline value.p.7
- With cash indexed at 100, remaining planned capital expenditure exceeds 3,000, and 40%–50% of cash remains restricted.p.7
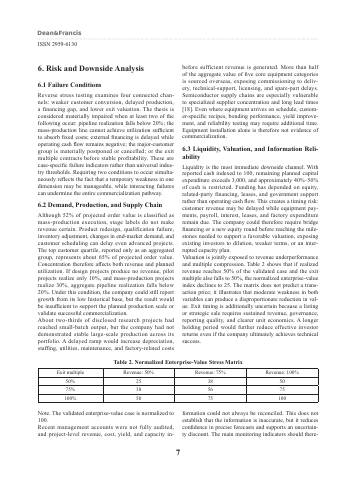
- If realized revenue and exit multiples both fall to 50% of base assumptions, the enterprise value index contracts to 25.p.7
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
 p.8
 p.9
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.