The Influence of EPS, ROA, DER, and Underwriter Reputation on Stock Underpricing in Manufacturing Companies Conducting IPOs on the Indonesia Stock Exchange (2022-2025) (JAMBURA Jurnal Ilmiah Manajemen dan Bisnis)
SaveSummary
- The research analyzes a total population of 110 manufacturing firms executing Initial Public Offerings on the Indonesia Stock Exchange between 2022 and 2025.p.1
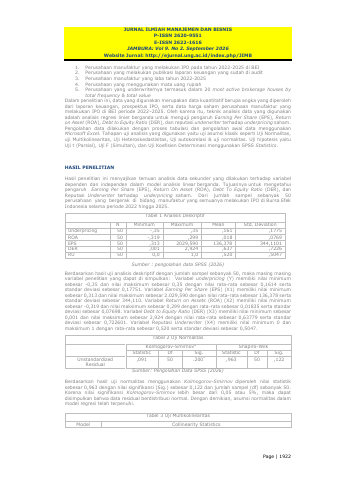
- The descriptive statistics for the 50 sampled companies demonstrate an average underpricing level of 0,1614, ranging from a minimum of -0,35 to a maximum of 0,35.p.3
- Sampled manufacturing firms showed an average Earnings Per Share of 136,378 and an average Debt to Equity Ratio of 0,63779.p.3
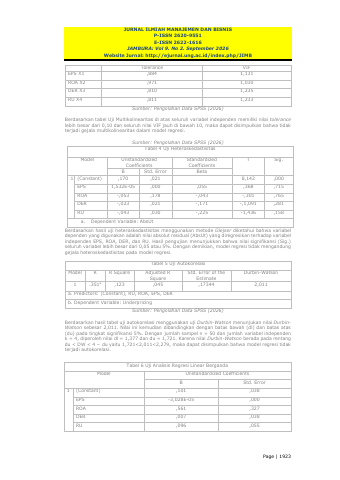
- The multiple linear regression model produced an R Square of 0,123, showing that the four analyzed variables explain 12,3% of underpricing variation, while 87,7% is explained by external factors.p.5
- Partial hypothesis testing revealed that Earnings Per Share (sig. 0,694) and Debt to Equity Ratio (sig. 0,861) have no statistically significant effect on underpricing.p.5
- Return on Assets (sig. 0,093) and underwriter reputation (sig. 0,085) also showed no statistically significant influence on IPO underpricing at the 5% significance level.p.5
- Simultaneous F-test analysis yielded an F-statistic of 1,582 with a significance value of 0,195, confirming no combined significant effect on stock underpricing.p.6
Key insights
- 1. Earnings Per Share has a negative coefficient of -0,00003028 and does not significantly impact IPO underpricing (significance of 0,694).p.5
- 2. Return on Assets demonstrates a positive coefficient of 0,561 but fails to reach statistical significance at the 5% level (significance of 0,093).p.5
- 3. Debt to Equity Ratio shows an insignificant partial effect on IPO underpricing with a p-value of 0,861.p.5
- 4. Underwriter reputation does not significantly reduce or explain underpricing among Indonesian manufacturing IPOs, recording a significance value of 0,085.p.5
- 5. The tested model exhibits an Adjusted R Square of 0,045, reflecting that the explanatory power of internal financials and underwriter prestige on IPO underpricing is only 4,5%.p.5
- 6. Simultaneous regression testing confirms that EPS, ROA, DER, and underwriter reputation together do not significantly determine underpricing levels (F-value of 1,582).p.6
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
 p.8
 p.9
 p.10
 p.11
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.