The Effect of Firm Size on Initial Return with Lead Underwriter Reputation as a Moderating Variable in IPO Companies 2023-2025 (Jurnal Ilmiah Metansi (Manajemen dan Akuntansi))
Summary
- The study examines how firm size affects initial return on the first day of secondary market trading, using lead underwriter reputation as a moderating variable for 134 companies conducting an IPO between 2023 and 2025.p.1
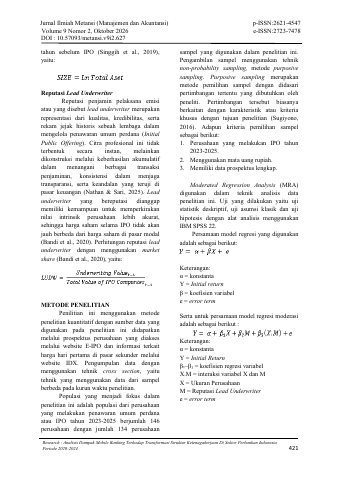
- Out of a total population of 146 companies conducting IPOs during the 2023–2025 period, 134 firms met the purposive sampling criteria of using Indonesian rupiah and providing complete prospectus data.p.4
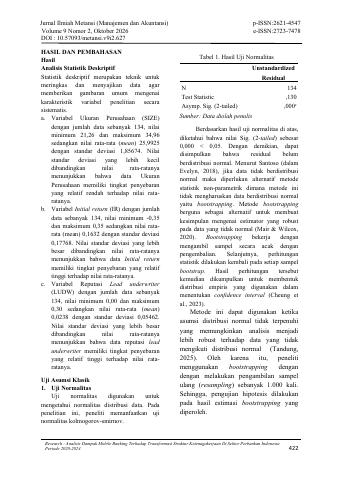
- Bootstrapping resampling of 1,000 iterations was applied due to non-normal residual distribution with an asymptotic significance of 0.000.p.5
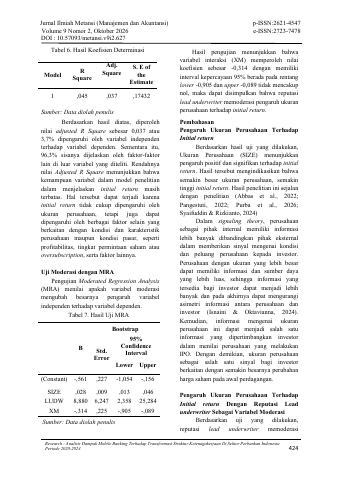
- Firm size shows a positive and statistically significant effect on initial return, while the adjusted R-squared indicates that the model explains 3.7% of initial return variation.p.7
- Moderated Regression Analysis shows that lead underwriter reputation negatively moderates the effect of firm size on initial return, with an interaction coefficient of -0.314.p.7
Key insights
- Firm size positively affects initial return, indicating that larger companies tend to experience larger price changes on their first trading day.p.7
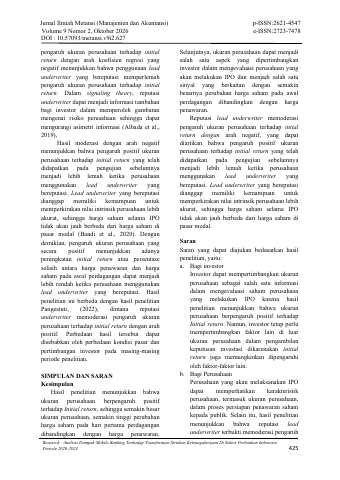
- Lead underwriter reputation negatively moderates the relationship between firm size and initial return, weakening the positive impact of firm size on first-day returns.p.8
- Reputable lead underwriters are considered better able to estimate the intrinsic value of an issuing company, resulting in IPO offer prices that align more closely with secondary market prices.p.8
- The research model yields an adjusted R-square of 0.037, meaning 96.3% of initial return variance is driven by other factors such as profitability and oversubscription.p.7
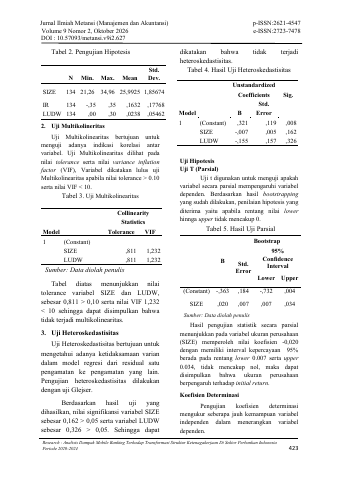
- No multicollinearity or heteroskedasticity issues were identified, with VIF values of 1.232 and Glejser test significance above 0.05 for all variables.p.6
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
 p.8
 p.9
 p.10
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.