Sustainability Scores and Tax Risk Differently Moderate Corporate Tax Avoidance Valuation (Indonesian Journal of Innovation Studies)
Summary
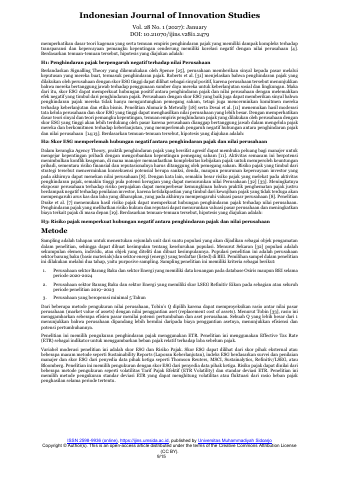
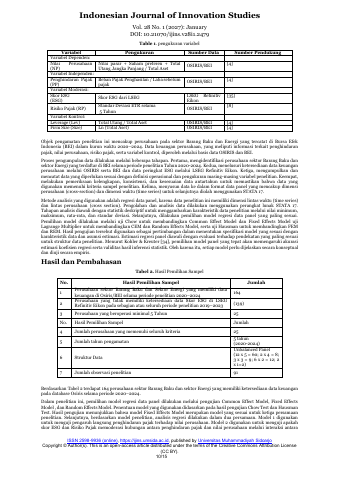
- The study analyzes an unbalanced panel of 91 observations from 25 basic materials and energy companies during 2020–2024.p.6
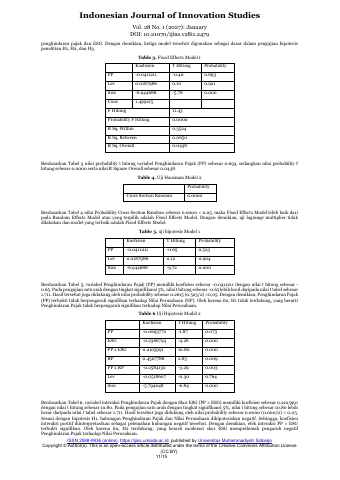
- Corporate tax avoidance showed no statistically significant direct relationship with firm value (p = 0.523).p.6
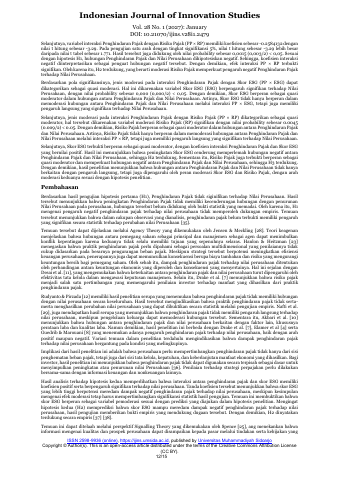
- ESG scores exhibited a positive moderation effect on the tax avoidance valuation relationship (β = 0.211; p < 0.001).p.6
- Tax risk demonstrated a negative moderation effect on the tax avoidance valuation relationship (β = −0.258; p = 0.003).p.6
- Out of 164 basic materials and energy companies listed on the Indonesia Stock Exchange, 139 were excluded due to missing ESG data in LSEG Refinitiv Eikon.p.10
- Firm size showed a statistically significant negative coefficient of -5.794048 with p = 0.000 in the fixed effects model.p.11
Key insights
- Tax avoidance does not have a statistically significant direct impact on firm value.p.6
- Strong ESG performance weakens the negative perception and impact of corporate tax avoidance on market valuation.p.6
- Higher corporate tax risk amplifies the negative impact of tax avoidance on firm valuation.p.6
- The research sample was refined from 164 companies to 25 firms operating for at least 5 years with available ESG scores.p.10
- Both ESG scores and tax risk serve as quasi-moderators because they display both significant interaction terms and direct effects on firm value.p.12
- Information disclosure regarding ESG practices can help neutralize adverse investor reactions to tax reduction strategies.p.13
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
 p.8
 p.9
 p.10
 p.11
 p.12
 p.13
 p.14
 p.15
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.