Electronic Banking Services and Their Role in Enhancing Financial Performance of Commercial Banks in Ethiopia (Academic research)
Summary
- Initial ATM adoption in Ethiopia began in the early 2000s, followed by mobile and internet banking growth after 2011.p.2
- Debit cards, ATMs, and mobile banking demonstrated statistically significant positive effects on profit after tax.p.3
- ATMs and mobile banking significantly enhanced return on equity, whereas point-of-sale terminals exerted a significant negative effect.p.3
- Internet banking yielded statistically insignificant effects on both profit after tax and return on equity.p.4
- Inflation consistently acted as a negative factor that eroded bank profitability and weakened electronic banking benefits.p.4
Key insights
- ATMs and mobile banking serve as the primary electronic channels driving profitability and shareholder returns in Ethiopian commercial banks.p.3
- Point-of-sale terminals negatively impact return on equity due to high maintenance expenses and low customer uptake.p.3
- Infrastructural constraints and limited internet penetration prevent internet banking from generating measurable financial returns.p.4
- Macroeconomic inflation undermines financial performance gains derived from e-banking innovation.p.4
- Ethiopian e-banking expansion lags behind regional East African peers such as Kenya and Tanzania.p.2
Pages
 p.1
 p.2
 p.3
 p.4
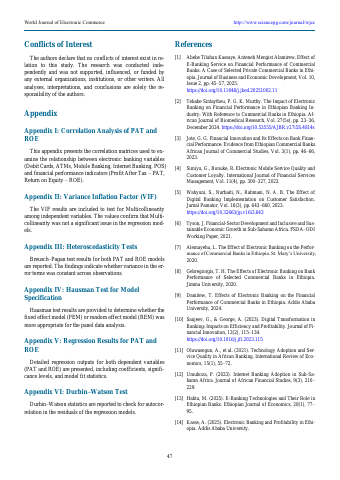 p.5
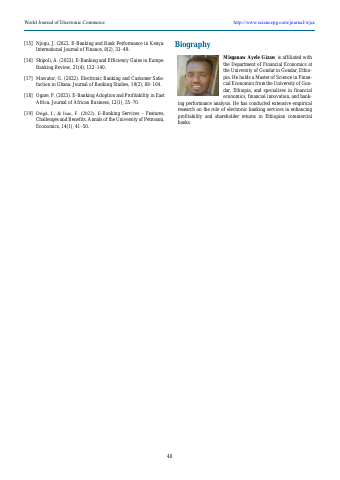 p.6
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.