Early Evaluation of the Effectiveness of Final Income Tax Expenditure for MSMEs as a Public Policy Instrument: Implementation of Government Regulation No. 20 of 2026 in Indonesia (Educoretax)
SaveSummary
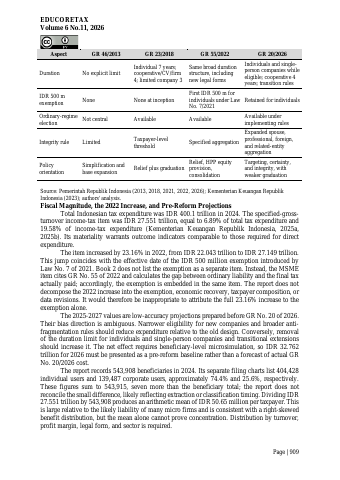
- In 2024 the final income tax expenditure reached IDR 27.551 trillion for 543,908 beneficiaries, an arithmetic mean of IDR 50.65 million per taxpayer.p.1
- The item equals 6.89% of total tax expenditure (IDR 400.1 trillion) and 19.58% of income-tax expenditure.p.7
- The item rose by 23.16% in 2022, from IDR 22.043 trillion to IDR 27.149 trillion.p.7
- The pre-reform report projected IDR 32.762 trillion for 2026.p.2
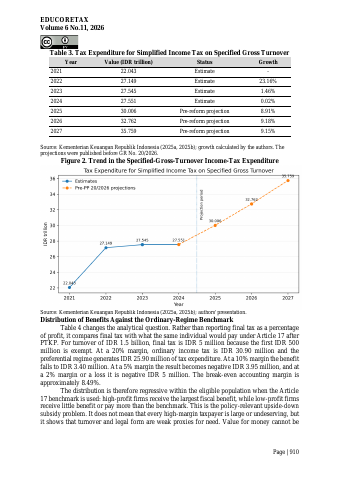
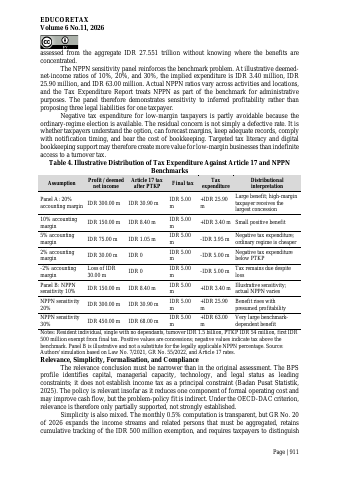
- For a taxpayer with IDR 1.5 billion turnover, tax expenditure is IDR 25.90 million at a 20% margin, IDR 3.40 million at 10%, and negative IDR 3.95 million at 5%.p.1
- The break-even accounting margin is approximately 8.49%.p.8
- IDR 4.8 billion is both the final income-tax ceiling and the VAT threshold, creating a double notch.p.1
Key insights
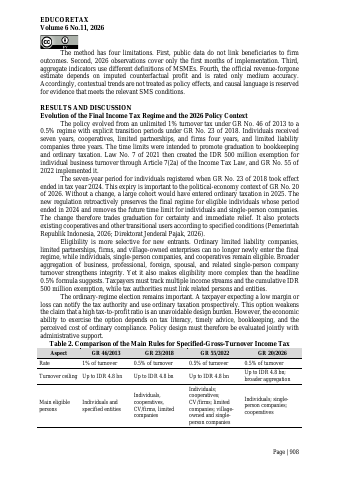
- The policy moved from a 1% turnover tax under GR No. 46 of 2013 to a 0.5% regime under GR No. 23 of 2018.p.6
- Law No. 7 of 2021 created an IDR 500 million exemption for individual business turnover.p.6
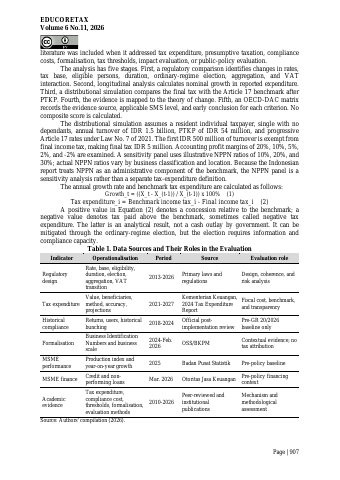
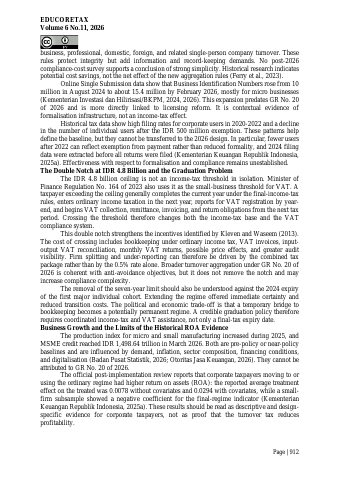
- Business Identification Numbers rose from 10 million in August 2024 to about 15.4 million by February 2026, a trend linked to licensing reform rather than the tax regime.p.10
- Illustrative deemed net income ratios of 10%, 20% and 30% imply expenditure of IDR 3.40 million, IDR 25.90 million and IDR 63.00 million.p.9
- Benefits rise with profitability, resembling an upside-down subsidy, while low-margin firms may face negative tax expenditure.p.13
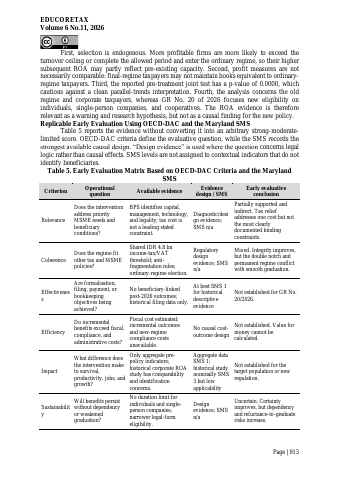
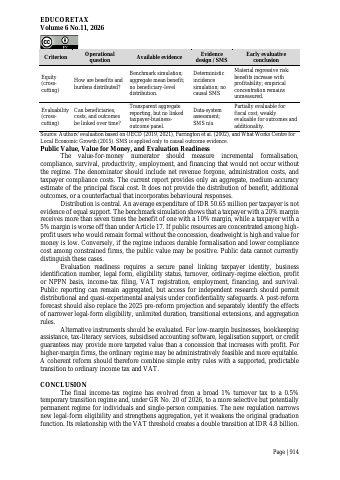
- Relevance and simplicity are only partially supported, and effectiveness and impact cannot be established without post-2026 beneficiary-linked data.p.13
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
 p.8
 p.9
 p.10
 p.11
 p.12
 p.13
 p.14
 p.15
 p.16
Funders mentioned
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.