Determinants of Profitability in Indonesian Commercial Banks (KBMI 3 and 4) in the Era of Digital Acceleration (Value Jurnal Manajemen dan Akuntansi)
Summary
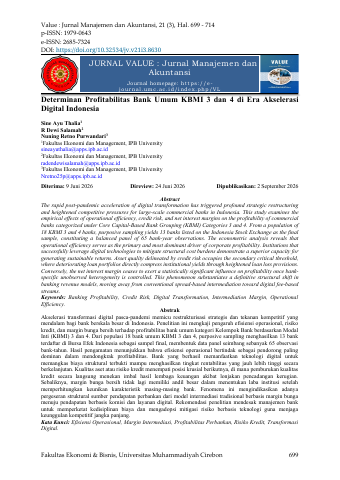
- National digital payment transactions in Indonesia reached 43.5 billion transactions in 2024, driven by a 175.2% year-on-year surge in QRIS and 62.4% growth in BI-FAST.p.2
- Physical commercial bank branch offices in Indonesia declined from 32,366 units in 2021 to 23,899 units in 2024 amid accelerating digital adoption.p.2
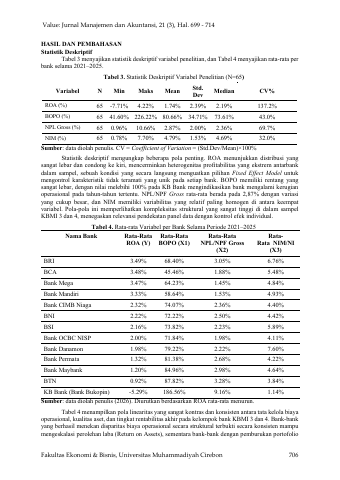
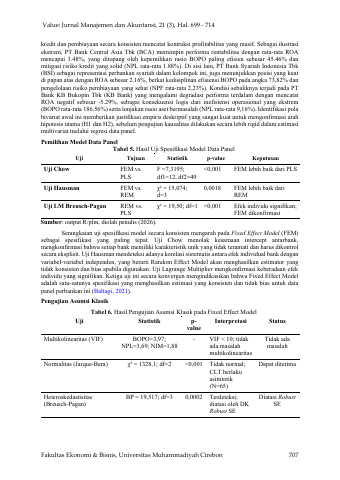
- BCA recorded the highest average profitability in the sample with an average ROA of 3.48%, whereas KB Bank registered an average ROA of -5.29%.p.9
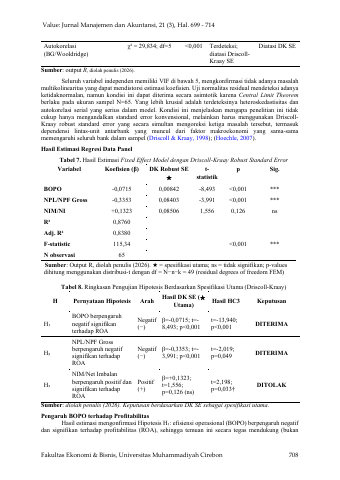
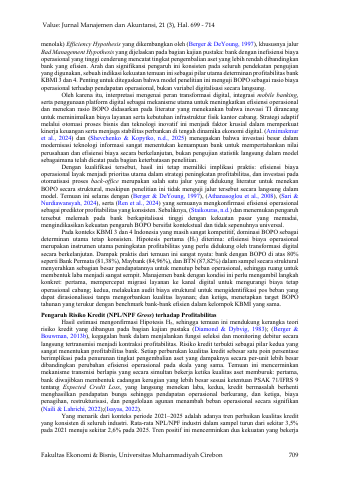
- Operational efficiency (BOPO) demonstrated a statistically significant negative impact on bank ROA, yielding a regression coefficient of -0.0715.p.10
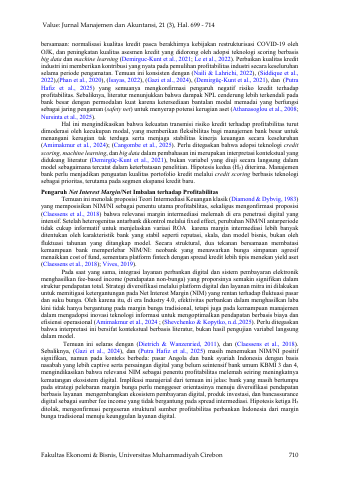
- Credit risk (NPL/NPF Gross) compressed commercial bank profitability significantly, with a regression coefficient of -0.3353.p.10
- Net interest margin (NIM/NI) lost statistical significance in explaining ROA (t-statistic = 1.556, p-value = 0.126) after controlling for bank fixed effects.p.10
Key insights
- Operational efficiency serves as the primary and most dominant determinant of corporate profitability for large Indonesian commercial banks.p.1
- Deteriorating credit risk directly reduces bank profitability by forcing higher loan loss provisions.p.1
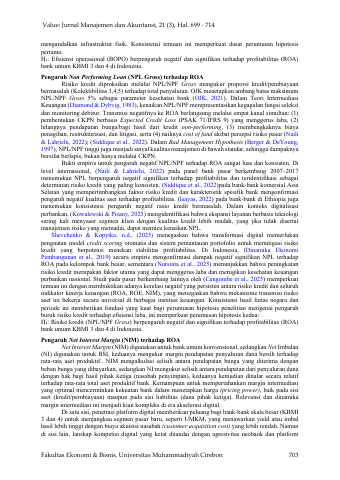
- Net interest margin loses its statistical significance on bank profitability once bank-specific unobserved heterogeneity is controlled.p.1
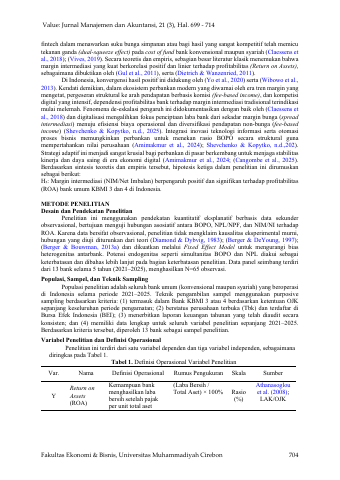
- Banks categorized under KBMI 3 and 4 command over 80% of total national banking industry assets in Indonesia.p.2
- Physical commercial bank branches shrank from 32,366 units in 2021 to 23,899 units in 2024 as banking shifted to digital channels.p.2
- BCA led sample profitability with an average ROA of 3.48%, supported by an efficient BOPO ratio of 45.46% and an average NPL of 1.88%.p.9
- Bank Syariah Indonesia (BSI) achieved an average ROA of 2.16% with a BOPO ratio of 73.82% and an NPF gross of 2.23%.p.9
- KB Bank suffered the sharpest performance drag with an average ROA of -5.29%, driven by an average BOPO of 186.56% and an NPL of 9.16%.p.9
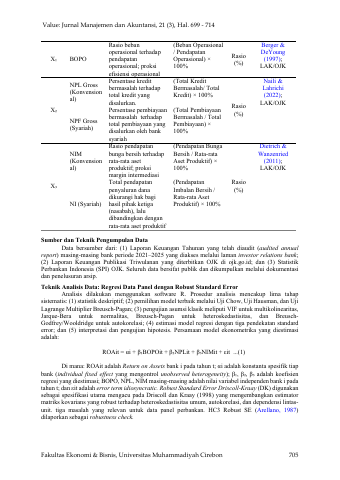
- The Fixed Effect Model using Driscoll-Kraay robust standard errors achieved an overall R-squared of 0.8760 and an adjusted R-squared of 0.8380.p.10
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
 p.8
 p.9
 p.10
 p.11
 p.12
 p.13
 p.14
 p.15
 p.16
Topics and entities
BankingRegulationBank IndonesiaOtoritas Jasa KeuanganPT Bank Central Asia TbkPT Bank CIMB Niaga TbkPT Bank Danamon Indonesia TbkPT Bank KB Bukopin TbkPT Bank Mandiri TbkPT Bank Maybank Indonesia TbkPT Bank Mega TbkPT Bank Negara Indonesia TbkPT Bank OCBC NISP TbkPT Bank Permata TbkPT Bank Rakyat Indonesia TbkPT Bank Syariah Indonesia TbkPT Bank Tabungan Negara Tbk
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.