Continued Acceptance of FinTech Payment Services: An Extended UTAUT Study on University Graduates of Bangladesh (Khulna University Business Review)
Summary
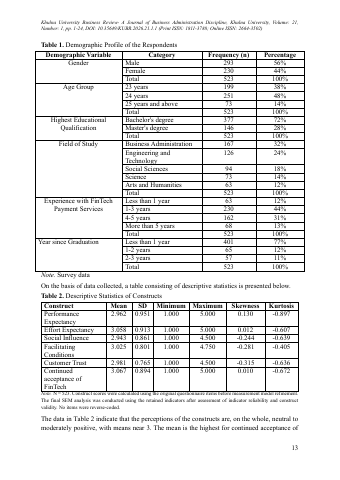
- Data were gathered from 523 university graduates across Dhaka, Chattogram, and Mymensingh to analyze FinTech payment acceptance.p.1
- The study achieved an effective response rate of 84.9% after receiving 523 valid responses out of 616 distributed questionnaires.p.10
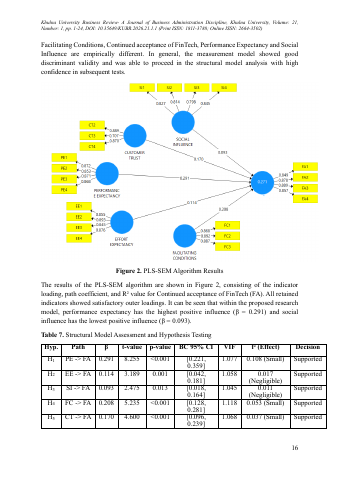
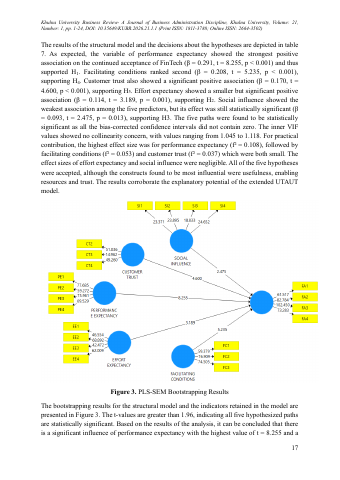
- Performance expectancy demonstrated the strongest positive relationship with continued acceptance of FinTech payment services (β = 0.291).p.16
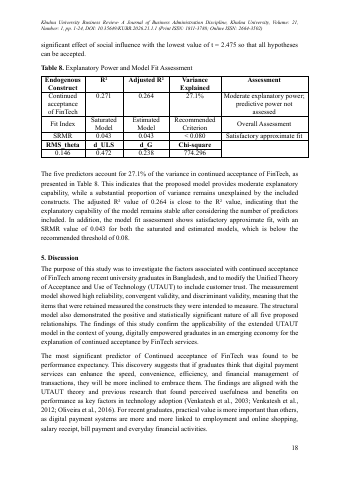
- The five structural factors accounted for 27.1% of the total variance in continued acceptance of FinTech payment services.p.18
Key insights
- Performance expectancy is the primary determinant of continued FinTech payment adoption among recent university graduates.p.1
- Facilitating conditions significantly drive sustained FinTech usage by providing necessary technical resources and digital knowledge.p.7
- Customer trust exerts a positive influence on continued usage by addressing privacy, fraud, and data security concerns.p.7
- Effort expectancy and social influence have statistically significant but relatively weaker practical impacts on payment service continuance.p.17
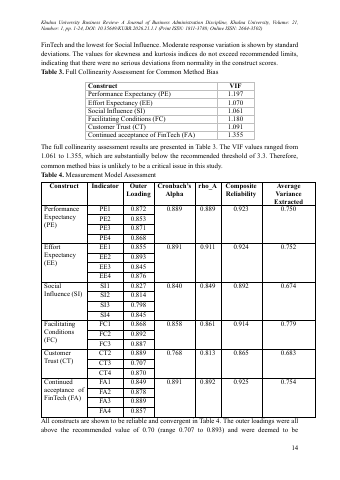
- Full collinearity testing yielded latent VIF values between 1.061 and 1.355, ruling out common method bias as a major threat.p.14
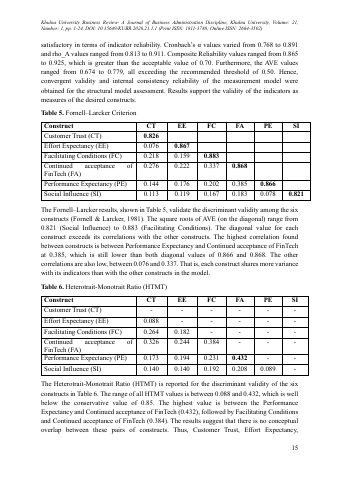
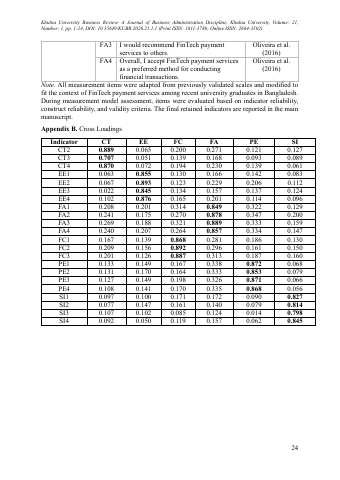
- Discriminant validity was established through HTMT values ranging from 0.088 to 0.432, well below the 0.85 threshold.p.15
- The structural model demonstrated satisfactory global fit with an SRMR value of 0.043.p.18
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
 p.8
 p.9
 p.10
 p.11
 p.12
 p.13
 p.14
 p.15
 p.16
 p.17
 p.18
 p.19
 p.20
 p.21
 p.22
 p.23
 p.24
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.