Analysis of the Contagion Effect Between the Cryptocurrency Market and the Indonesian Stock Market (Journal of Management)
SaveWhat changed
25.6% to 36.4%
Average rolling spillover index, 2018 to 2019 vs the COVID crash window p.9
Summary
- The study uses daily returns of Bitcoin, Ethereum, the Jakarta Composite Index and the IDX technology index from 3 January 2018 to 30 June 2026.p.1
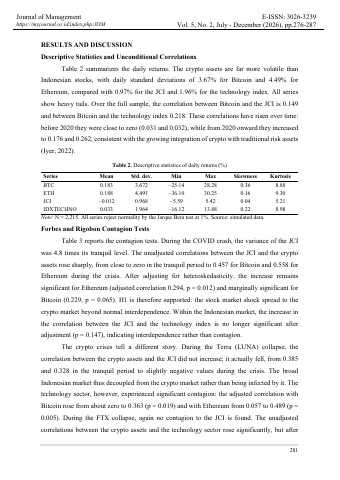
- Daily standard deviations are 3.67% for Bitcoin and 4.49% for Ethereum, versus 0.97% for the JCI and 1.96% for the technology index.p.6
- During the COVID crash the variance of the JCI was 4.8 times its tranquil level.p.6
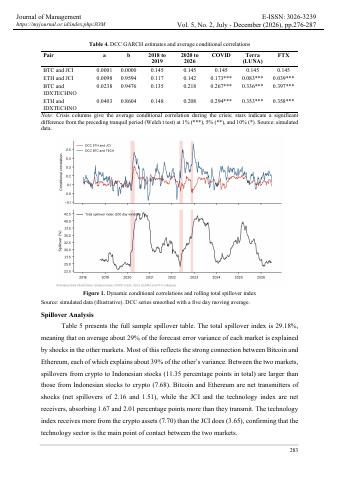
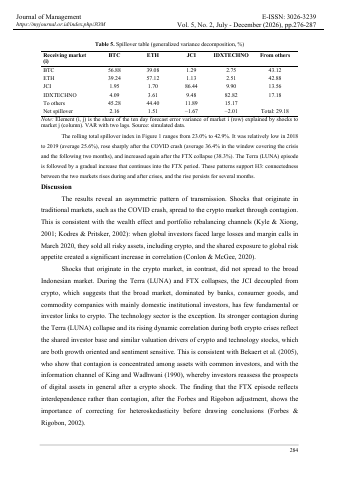
- The total spillover index is 29.18%.p.8
- Spillovers from crypto to Indonesian stocks total 11.35 percentage points, versus 7.68 from Indonesian stocks to crypto.p.8
- The rolling total spillover index ranges from 23.0% to 42.9%.p.9
Key insights
- The Bitcoin-JCI correlation is 0.149 over the full sample, and the Bitcoin-technology index correlation is 0.218.p.6
- Correlations before 2020 were close to zero (0.031 and 0.032) and rose to 0.176 and 0.262 from 2020 onward.p.6
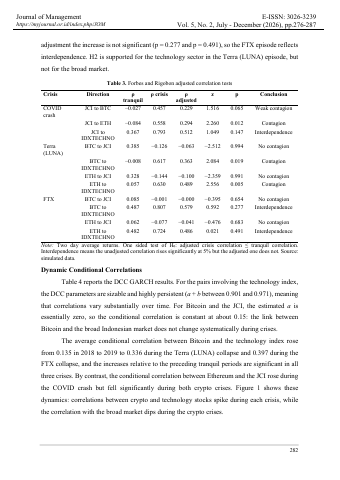
- After adjusting for heteroskedasticity, the COVID-crash increase stays significant for Ethereum (adjusted correlation 0.294, p = 0.012) and is marginal for Bitcoin (0.229, p = 0.065).p.6
- Bitcoin and Ethereum are net transmitters of shocks (net spillovers of 2.16 and 1.51), while the JCI and the technology index are net receivers.p.8
- The analysis is described as illustrative, and the tables are labelled as based on simulated data.p.10
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
 p.8
 p.9
 p.10
 p.11
 p.12
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.