A Transformer-Based Explainable Machine Learning Framework for Heterogeneous ESG Risk and Return Prediction Using Text Intelligence (Future Technology)
SaveSummary
- HET-ESGFormer is evaluated on 3,182 U.S.-listed firms over 2015 to 2024 using 10-K filings, sustainability reports, earnings call transcripts and ESG-tagged news.p.1
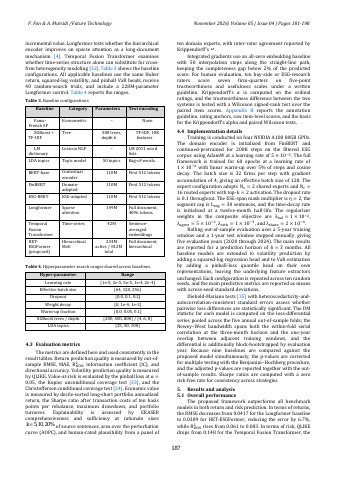
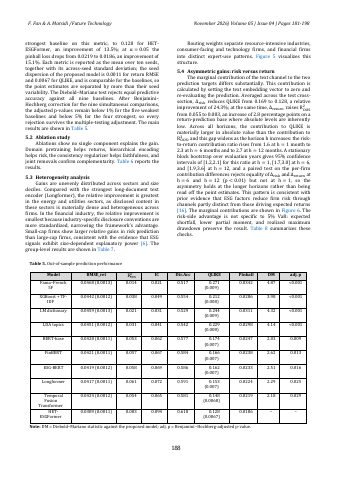
- Against nine baselines, it reduces return RMSE from 0.0417 to 0.0389 and QLIKE from 0.148 to 0.128.p.1
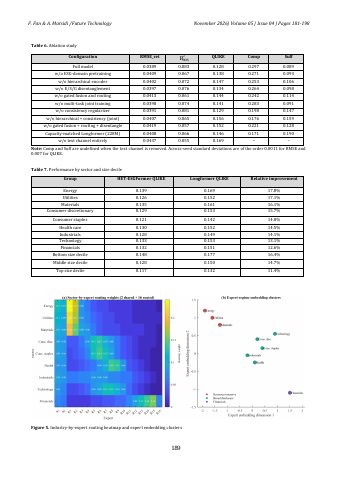
- Zeroing the text channel shows that it reduces QLIKE from 0.169 to 0.128, a relative improvement of 24.3%.p.8
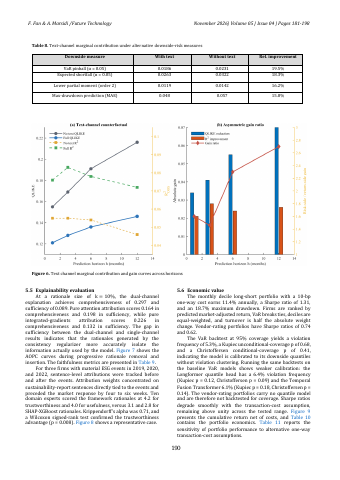
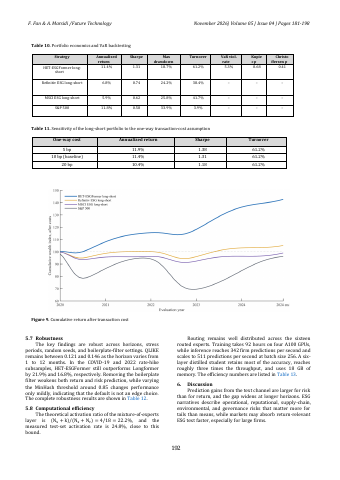
- The monthly decile long-short portfolio with a 10-bp one-way cost earns 11.4% annually, a Sharpe ratio of 1.31, and an 18.7% maximum drawdown.p.10
- The VaR backtest at 95% coverage yields a violation frequency of 5.3%.p.10
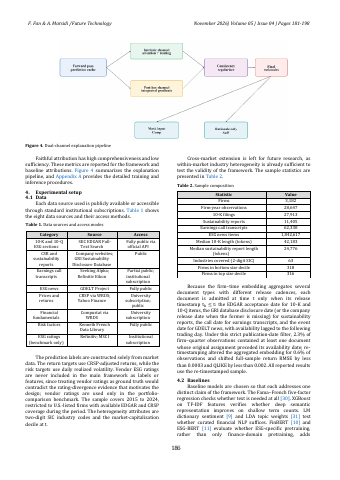
- The sample contains 28,647 firm-year observations and 1,842,617 ESG news items.p.6
Key insights
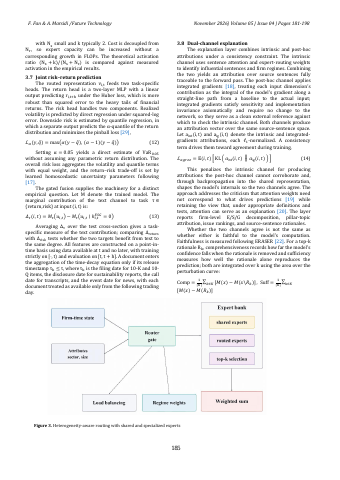
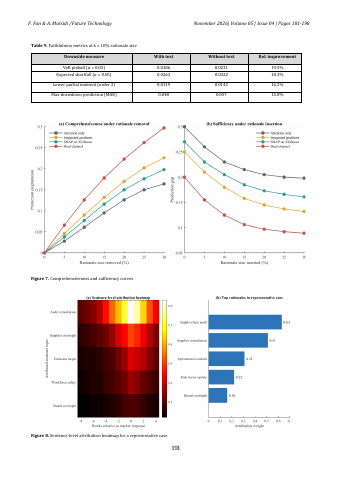
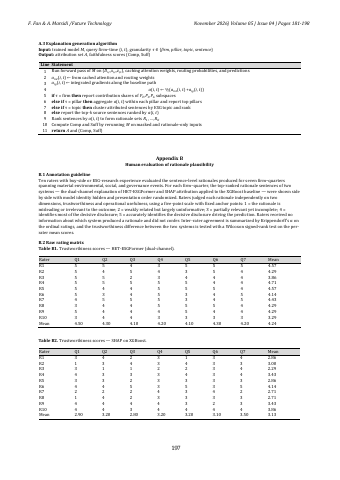
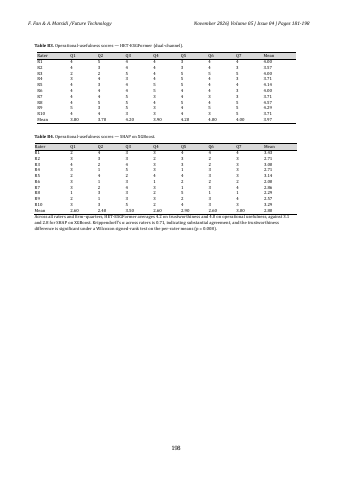
- At a rationale size of k = 10%, the dual-channel explanation achieves comprehensiveness of 0.297 and sufficiency of 0.089.p.10
- At α = 0.05 the pinball loss drops from 0.0219 to 0.0186, an improvement of 15.1%.p.8
- The text channel raises R2OOS from 0.055 to 0.083, an increase of 2.8 percentage points.p.8
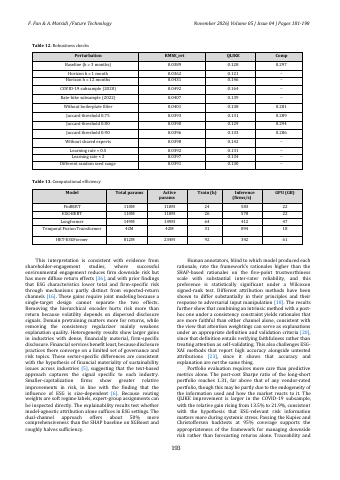
- In the COVID-19 and 2022 rate-hike subsamples, HET-ESGFormer still outperforms Longformer by 21.9% and 16.8%, respectively.p.12
- QLIKE remains between 0.121 and 0.146 as the horizon varies from 1 to 12 months.p.12
- Vendor-rating portfolios have Sharpe ratios of 0.74 and 0.62.p.10
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
 p.8
 p.9
 p.10
 p.11
 p.12
 p.13
 p.14
 p.15
 p.16
 p.17
 p.18
Funders mentioned
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.