Working Capital Management and Firm Value in Bangladesh: Do Cash Conversion Cycle Components Matter Differently? (International Journal of Economics and Finance)
SaveSummary
- The study covers 20 manufacturing firms listed on the Dhaka Stock Exchange from 2018 to 2022.p.1
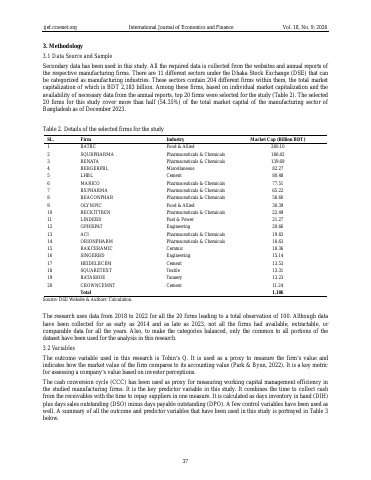
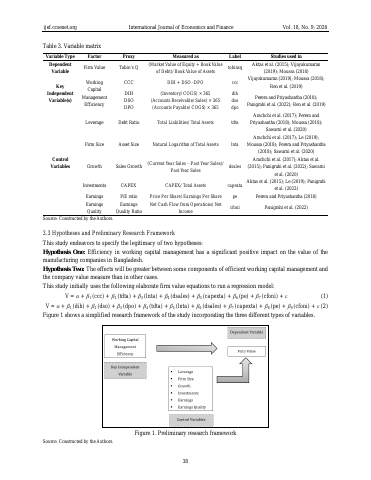
- The 20 selected firms cover 54.35% of the manufacturing sector's market capital, out of 204 firms with total market capitalization of BDT 2,183 billion.p.4
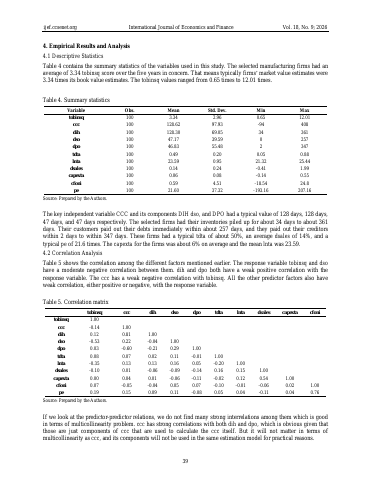
- The average Tobin's Q was 3.34, ranging from 0.65 to 12.01.p.6
- Typical values were 128 days for CCC, 128 days for DIH, 47 days for DSO and 47 days for DPO.p.6
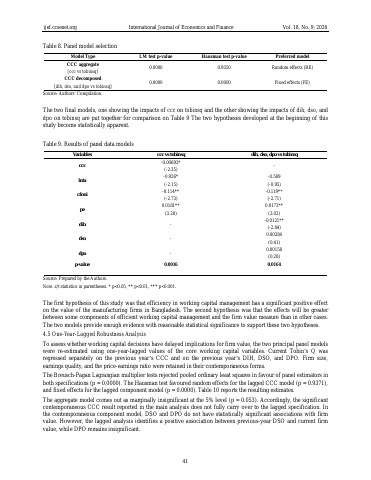
- The CCC coefficient is -0.00693 and the DIH coefficient is -0.0121, while DSO (0.00284) and DPO (0.00158) are insignificant.p.8
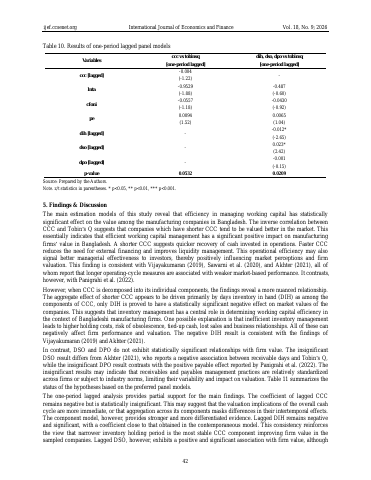
- In lagged models DIH is -0.012 and DSO is 0.023, both significant, while DPO is -0.001.p.9
Key insights
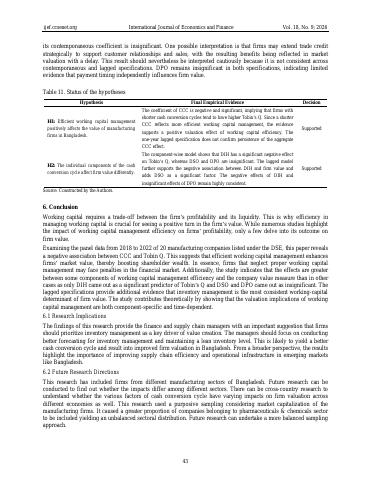
- Shorter cash conversion cycles are associated with higher Tobin's Q, supporting a positive valuation effect of working capital efficiency.p.10
- Inventory holding period (DIH) has a significant negative effect on firm value in both contemporaneous and lagged models.p.10
- DSO is insignificant contemporaneously but significant in the lagged model, so its effect should be interpreted cautiously.p.10
- DPO remains insignificant in both specifications, so there is limited evidence that payment timing independently influences firm value.p.10
- The one-year lagged specification does not confirm persistence of the aggregate CCC effect.p.10
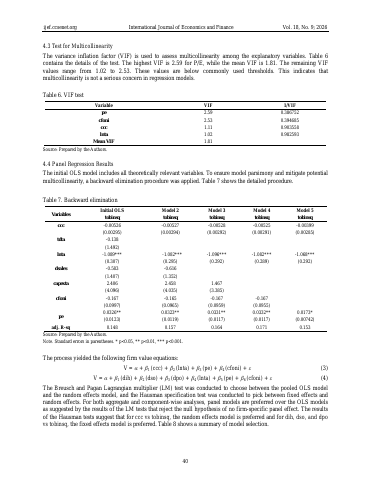
- The highest VIF is 2.59 and the mean VIF is 1.81, so multicollinearity is not a serious concern.p.7
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
 p.8
 p.9
 p.10
 p.11
 p.12
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.