The Influence of ESG Disclosure, Institutional Ownership, and CEO Characteristics on Firm Value: Empirical Evidence from Eight Banks in Indonesia (Jurnal Akademi Akuntansi Indonesia Padang)
SaveSummary
- The study analyses ESG disclosure, institutional ownership and CEO characteristics against firm value at eight Indonesian banks over 2021–2025, using a balanced panel regression.p.1
- The sample yields 40 bank-year observations and is analysed with Common Effect, Fixed Effect and Random Effect estimation.p.1
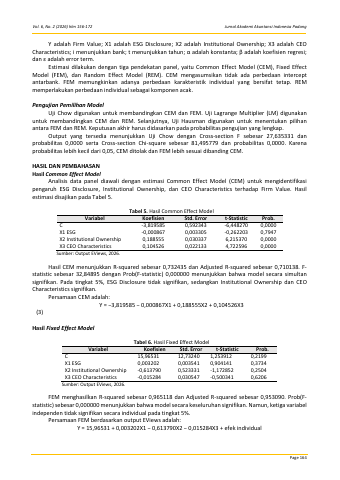
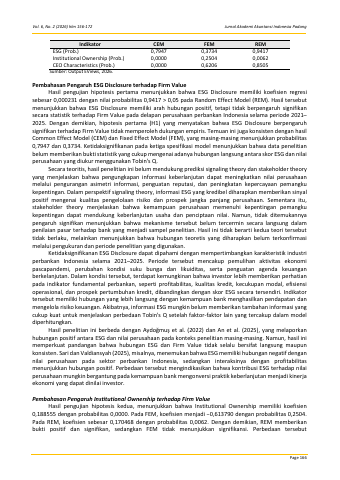
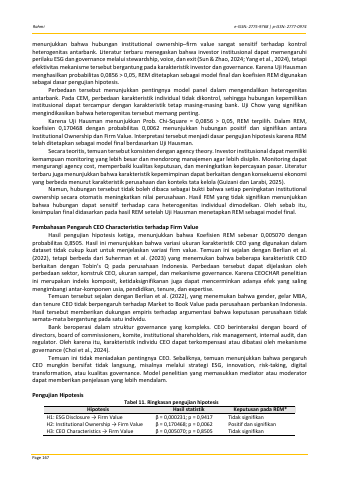
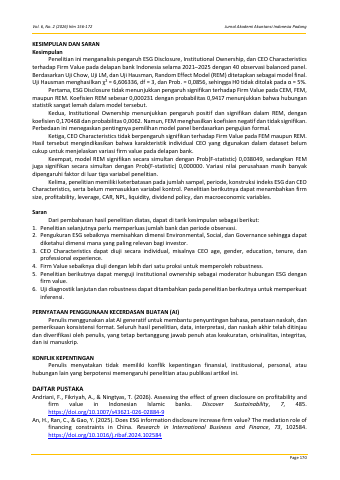
- In the Random Effect model, ESG disclosure has a coefficient of 0.000231 with a probability of 0.9417, so it is not significant.p.1
- In the Random Effect model, institutional ownership has a coefficient of 0.170468 with a probability of 0.0062, a positive and significant effect.p.1
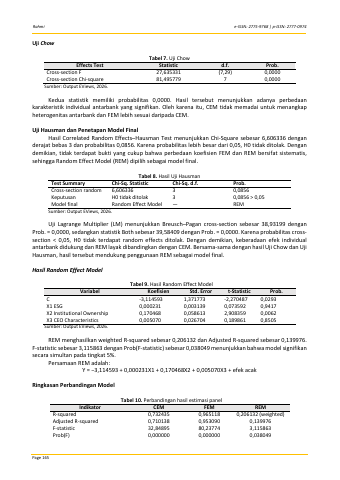
- The Hausman test gives a Chi-Square of 6.606336 with a probability of 0.0856, so the Random Effect Model is chosen as the final model.p.10
- The Random Effect model is jointly significant with a Prob(F-statistic) of 0.038049, while much of the variation in firm value remains unexplained by the three variables.p.15
Key insights
- Institutional ownership has a probability of 0.0000 in CEM, 0.2504 in FEM and 0.0062 in REM, so its significance depends on the model used.p.11
- CEO characteristics are not significant in the Fixed Effect and Random Effect models, so the CEO profile index does not explain firm value variation across the eight banks.p.15
- The Chow test gives a Cross-section F of 27.635331 with a probability of 0.0000, showing significant differences between banks.p.10
- The Fixed Effect estimate for institutional ownership is negative and insignificant, which shows the importance of choosing the panel model by formal tests.p.15
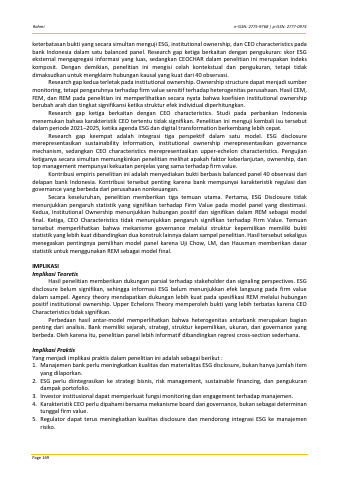
- The authors note limitations in sample size, period and index construction, and the absence of control variables.p.15
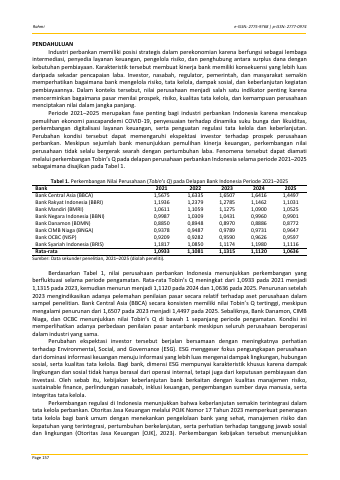
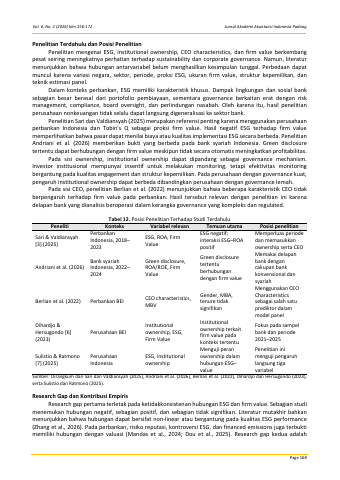
- In March 2026 the Indonesian financial regulator OJK issued the Banking Sustainability Maturity Assessment Report (SMART) 2025, which pointed to a need to integrate climate and sustainability risk into core risk management.p.3
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
 p.8
 p.9
 p.10
 p.11
 p.12
 p.13
 p.14
 p.15
 p.16
 p.17
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.