Tax Management in the Energy Sector: CSR Disclosure as Moderator and Profitability as Mediator in the Governance-Finance Nexus (International Journal of Accounting Management Economics and Social Sciences (IJAMESC))
SaveSummary
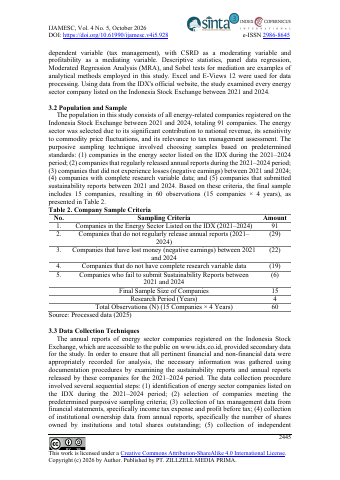
- The study covers 15 energy companies listed on the Indonesia Stock Exchange, selected from a population of 91, yielding 60 observations for 2021 to 2024.p.1
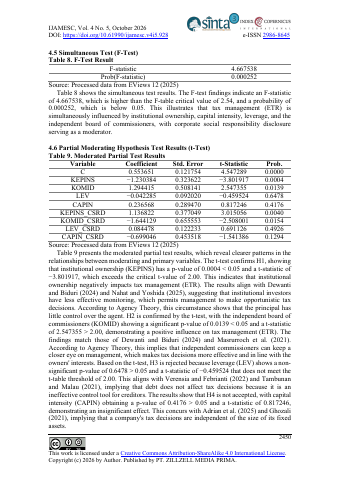
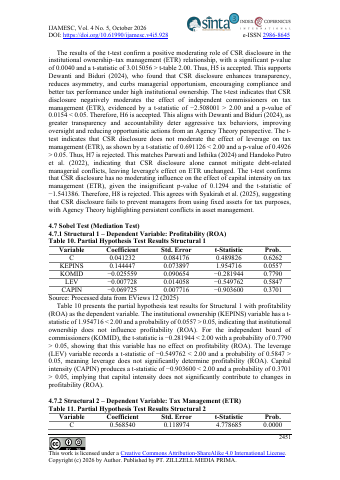
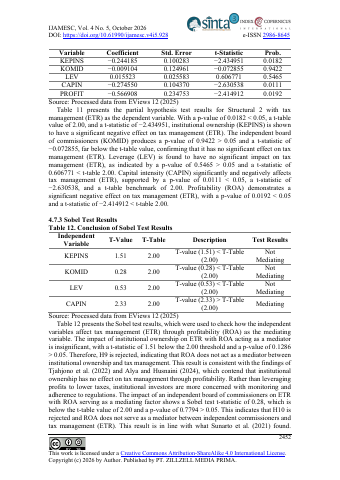
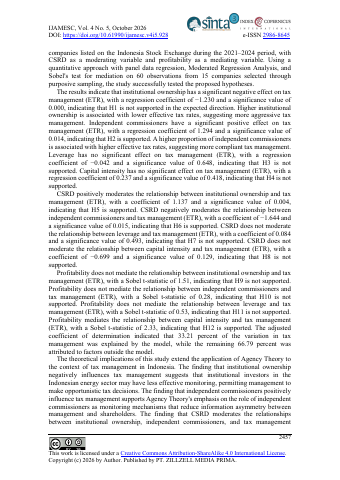
- Institutional ownership has a significant negative effect on ETR (β = −1.230, p = 0.000), while independent commissioners have a significant positive effect (β = 1.294, p = 0.014).p.1
- CSR disclosure strengthened the relationship between institutional ownership and ETR (β = 1.137, p = 0.004).p.1
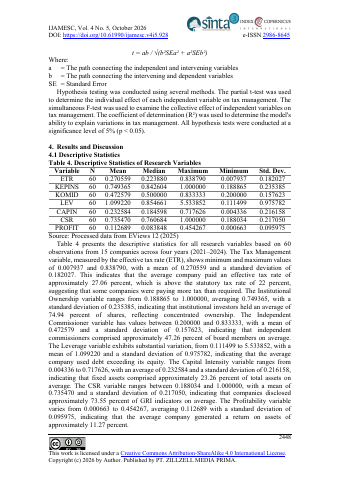
- The average effective tax rate was approximately 27.06 percent.p.15
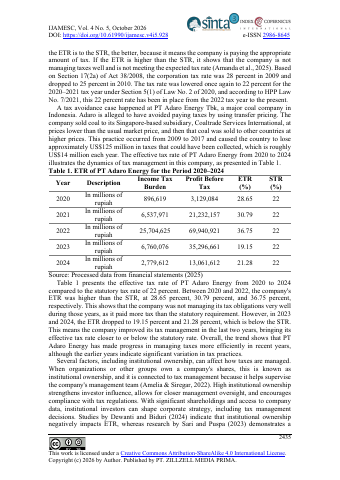
- The Adaro Energy transfer-pricing case cost the state approximately US$125 million in taxes, roughly US$14 million each year, from 2009 to 2017.p.2
- The 22 percent corporate tax rate has applied from the 2022 tax year to the present.p.2
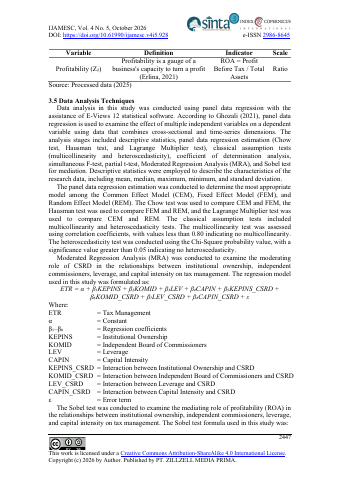
- The F-test gives an F-statistic of 4.667538 with a probability of 0.000252.p.17
Key insights
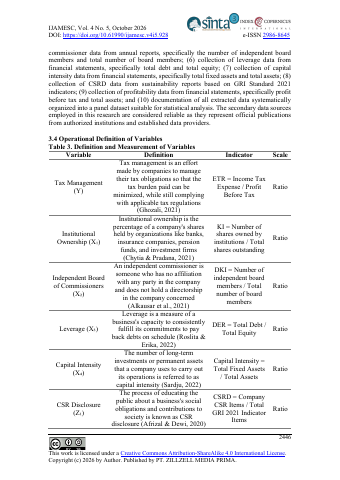
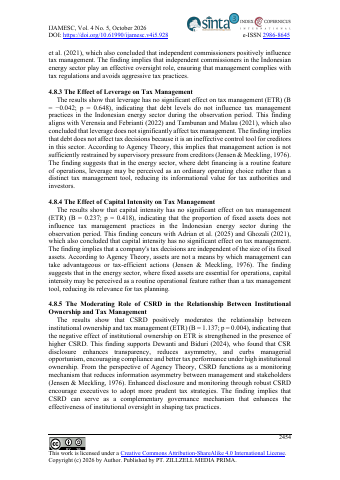
- Leverage has no significant effect on ETR (B = −0.042; p = 0.648).p.21
- Capital intensity has no significant direct effect on ETR (B = 0.237; p = 0.418).p.21
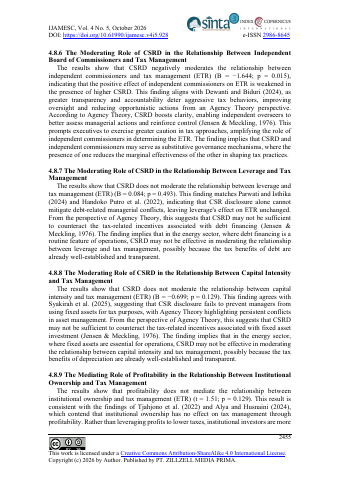
- CSR disclosure negatively moderates the effect of independent commissioners on ETR (B = −1.644; p = 0.015).p.22
- CSR disclosure does not moderate the effect of leverage on ETR (B = 0.084; p = 0.493).p.22
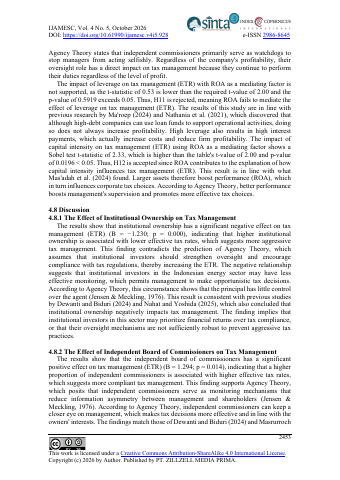
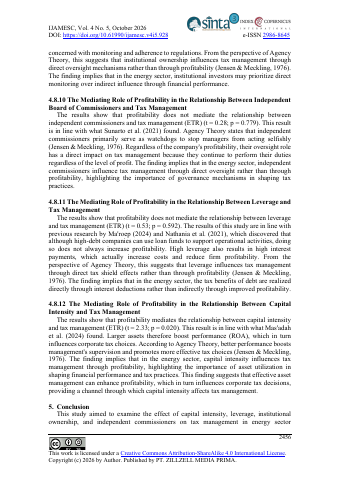
- Profitability (ROA) mediates the effect of capital intensity on ETR, with a Sobel t-statistic of 2.33 and p-value of 0.0196.p.20
- Profitability does not mediate the effect of independent commissioners on ETR (t = 0.28; p = 0.779).p.23
- Profitability does not mediate the effect of leverage on ETR (t = 0.53; p = 0.592).p.23
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
 p.8
 p.9
 p.10
 p.11
 p.12
 p.13
 p.14
 p.15
 p.16
 p.17
 p.18
 p.19
 p.20
 p.21
 p.22
 p.23
 p.24
 p.25
 p.26
 p.27
 p.28
 p.29
Funders mentioned
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.