Effect of Accruals Quality on the Firm Value of Construction and Allied Firms Listed at the Nairobi Securities Exchange, Kenya (East African Journal of Business and Economics)
SaveSummary
- The study uses panel data from four firms covering 2015–2025, measuring accruals quality with the Dechow and Dichev model and firm value with Tobin's Q.p.1
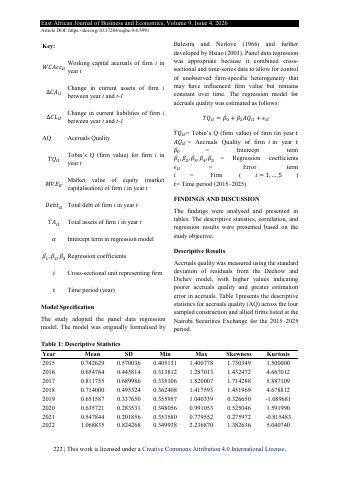
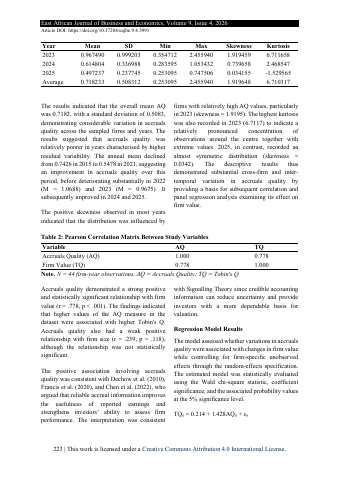
- Overall mean accruals quality (AQ) was 0.7182 with a standard deviation of 0.5083.p.10
- The annual mean AQ declined from 0.7426 in 2015 to 0.5478 in 2021, before deteriorating in 2022 (M = 1.0688).p.10
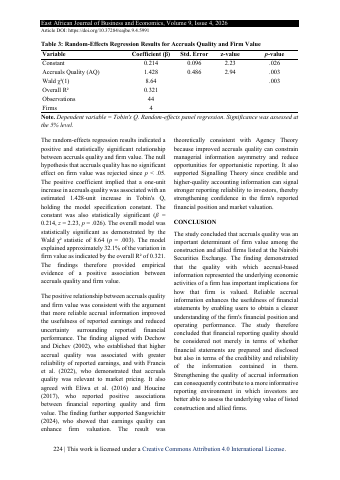
- The random-effects regression gives an accruals quality coefficient of 1.428 (p-value .003) on Tobin's Q.p.11
- The model has an overall R² of 0.321 and a Wald χ²(1) of 8.64, with 44 observations from 4 firms.p.11
- The study concludes that accruals quality is an important determinant of firm value among the listed construction and allied firms.p.11
Key insights
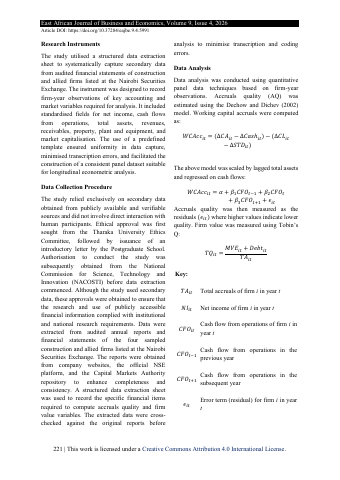
- Accruals quality was estimated as the residual of working capital accruals regressed on cash flows, where higher values indicate lower quality.p.8
- Accruals quality was relatively poorer in years with higher residual variability, notably 2022 and 2023.p.10
- In 2023 the AQ distribution showed positive skewness of 1.9195 and kurtosis of 6.7117, driven by a few firms with high AQ values.p.10
- The null hypothesis of no effect was rejected since p < .05.p.11
- A one-unit increase in the accruals quality measure is associated with an estimated 1.428-unit increase in Tobin's Q.p.11
- The model explains approximately 32.1% of the variation in firm value.p.11
- Results are consistent with Agency Theory and Signalling Theory, as credible accounting information strengthens investor confidence.p.11
- The study recommends that managers strengthen systems that generate, review and validate accrual-based information, and that the Capital Markets Authority continue strengthening reporting oversight.p.12
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
 p.8
 p.9
 p.10
 p.11
 p.12
 p.13
Funders mentioned
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.