Capital Adequacy, Profitability, Credit Risk, and Operational Efficiency in Indonesian Banks' Price to Book Value (Jurnal Relevansi Ekonomi Manajemen dan Bisnis)
SaveSummary
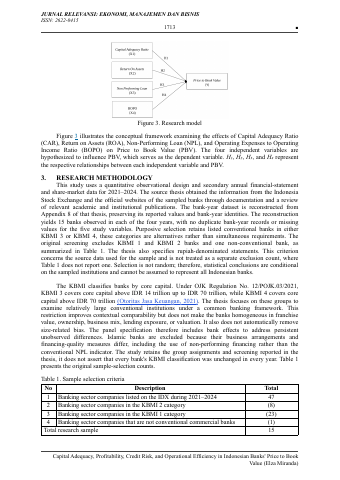
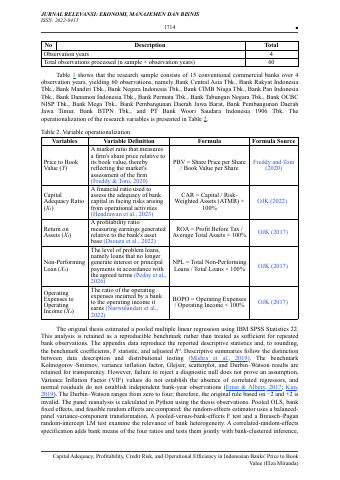
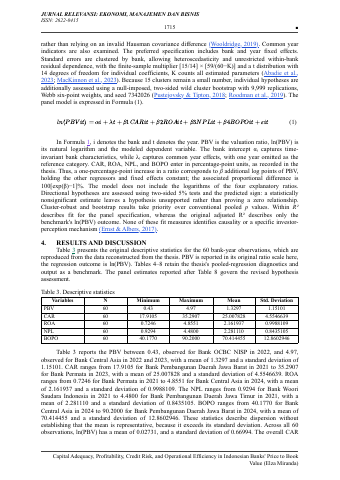
- The study covers 15 listed Indonesian conventional banks in KBMI 3 and KBMI 4 during 2021–2024, with 60 bank-year observations.p.1
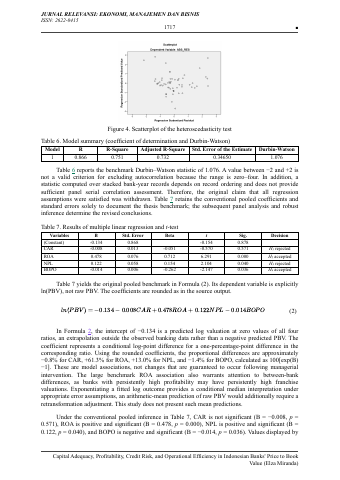
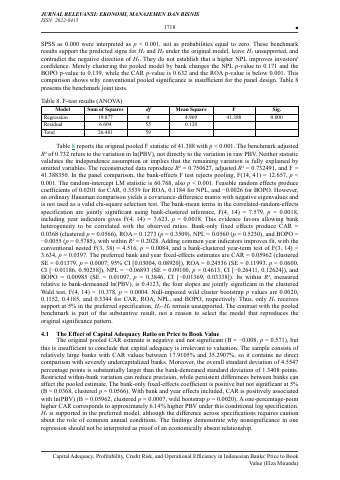
- In the preferred fixed-effects model, CAR is positively associated with ln(PBV) (B = 0.0596, p = 0.0007), while ROA (B = 0.2454, p = 0.0600) is not significant at 5%.p.1
- NPL (B = −0.0689, p = 0.4613) and BOPO (B = 0.0098, p = 0.3846) are not statistically significant, and wild cluster bootstrap supports only CAR (p = 0.0020).p.1
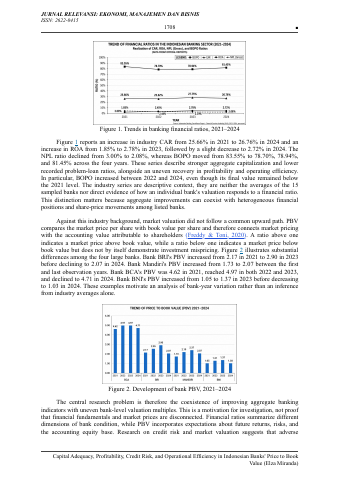
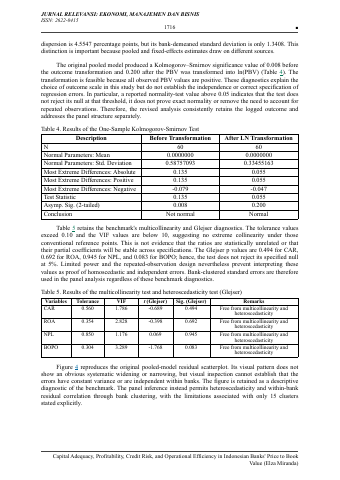
- Industry CAR rose from 25.66% in 2021 to 26.76% in 2024, while the NPL ratio declined from 3.00% to 2.08%.p.2
- Industry ROA rose from 1.85% to 2.78% in 2023, followed by a slight decrease to 2.72% in 2024.p.2
- Bank BRI's PBV increased from 2.17 in 2021 to 2.90 in 2023 before declining to 2.07 in 2024.p.2
Key insights
- Only CAR remains significantly associated with valuation once bank and year fixed effects and bank-clustered errors are used.p.1
- The benchmark positive NPL coefficient (B = 0.122) is specification-sensitive and does not show that the market rewards poor loans.p.1
- BOPO increased between 2022 and 2024 even though its final value remained below the 2021 level.p.2
- Market valuation did not follow a common upward path across the large banks.p.2
- A PBV ratio above one indicates a market price above book value but does not by itself demonstrate mispricing.p.2
- Clustering the pooled model by bank changes the NPL p-value to 0.171 and the BOPO p-value to 0.139.p.12
- The results are conditional observational associations, not causal effects, and only 15 bank clusters are available.p.15
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
 p.8
 p.9
 p.10
 p.11
 p.12
 p.13
 p.14
 p.15
 p.16
 p.17
 p.18
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.